CRYPTO
FintechZoom.io Nasdaq: How to Use the Platform for Charts, Data, and Market Insights

FintechZoom.io Nasdaq gives everyday investors a practical way to follow tech-heavy markets without needing a professional terminal. When people search for fintechzoom.io nasdaq, they usually want live index numbers, charts, and context on companies listed on the Nasdaq exchange. This guide explains what the platform actually offers, how its Nasdaq coverage works, and how to use the information responsibly.
The Nasdaq remains one of the most watched benchmarks in the world because it holds many of the companies driving innovation. Understanding both the exchange and the tools that track it helps you stay informed. FintechZoom positions itself as a financial media and data site rather than a brokerage, so you cannot place trades or hold funds there. Always confirm important numbers with your broker or an official source.
What Is FintechZoom.io and How Does It Relate to Nasdaq?
FintechZoom.io is a U.S.-based financial information platform that publishes market news, educational content, and data tools. Its Nasdaq section focuses on the Nasdaq Composite and related indexes. The site aggregates price movements, charts, and commentary so readers can see how technology and growth stocks are performing.
It is not affiliated with Nasdaq, Inc., the company that operates the exchange and calculates the official indexes. Nasdaq runs the market infrastructure and sets the rules for listings and index membership. FintechZoom.io simply presents publicly available market information in one place. The same distinction applies to fintechzoom.com, which has stated that the .io domain is not part of its network. Treat each site independently and verify any claims before relying on them.
Understanding Nasdaq Composite vs. Nasdaq-100 on FintechZoom.io
Many visitors land on fintechzoom.io nasdaq pages while looking for either the broad Nasdaq Composite or the more concentrated Nasdaq-100. The two indexes sound similar but track different groups of companies. Knowing the difference prevents confusion when you read charts or news.
| Feature | Nasdaq Composite | Nasdaq-100 |
|---|---|---|
| Number of companies | 3,000+ | About 100 |
| Includes financial firms | Yes | No |
| Size focus | All market caps | Large-cap only |
| Weighting | Market capitalization | Modified market cap with caps |
| Common use | Broad view of Nasdaq-listed stocks | Large non-financial growth and tech exposure |
| Popular ETF example | ONEQ | QQQ |
The Composite offers a wider snapshot of every eligible Nasdaq-listed company. The Nasdaq-100 concentrates on the largest non-financial names and has historically been more sensitive to big tech moves. FintechZoom.io pages often highlight both, so check which ticker or label appears on the chart you are viewing.
Key Tools Available in the FintechZoom.io Nasdaq Section
The platform groups several practical features under its Nasdaq coverage. Most are aimed at retail investors who want quick context rather than institutional-grade feeds.
| Tool | What It Provides | Typical User Benefit |
|---|---|---|
| Live price tracking | Current and recent values for the Composite and Nasdaq-100 | Quick check of daily direction |
| Interactive charts | Customizable timeframes, often powered by common charting libraries | Visual trend review without switching sites |
| Technical indicators | Moving averages, RSI, MACD, Bollinger Bands | Basic momentum and volatility signals |
| Sector heatmaps | Visual performance breakdown by industry | Spot which groups are leading or lagging |
| Earnings calendar | Upcoming reports for major listed companies | Prepare for volatility around results |
| News and commentary | Market-moving stories and analyst notes | Context behind price moves |
| Educational content | Explainers on indexes, trading basics, and related topics | Build understanding over time |
These tools work best as a starting point. Real-time data on free tiers can carry short delays, and predictive features should be treated as opinion rather than fact. Cross-check levels that matter to your decisions.
How to Read Nasdaq Charts Effectively
Charts on platforms like fintechzoom.io nasdaq become useful once you know what each element shows. Start with the price axis and time axis. Candlesticks or line charts display open, high, low, and close values for each period. Volume bars underneath reveal how much trading activity supported a move.
Moving averages smooth out short-term noise. A stock or index trading above a rising 50-day or 200-day average often signals positive longer-term momentum. Relative Strength Index (RSI) readings above 70 suggest overbought conditions; readings below 30 suggest oversold conditions. These are signals, not commands.
A practical example: suppose the Nasdaq-100 has risen sharply for several sessions and RSI sits near 75. The chart may look strong, yet the elevated reading warns that a pause or pullback is possible. Pair the chart with the earnings calendar and recent news to see whether the move has fundamental support.
Pros and Cons of Using FintechZoom.io for Nasdaq Coverage
Pros
- Centralized view of index levels, charts, and related news
- Accessible language aimed at non-professionals
- Coverage of both broad Composite and focused Nasdaq-100 views
- Educational material that explains concepts in plain terms
- No account required for basic reading
Cons
- Not an official Nasdaq source or a regulated data vendor
- Data may be delayed or aggregated from third parties
- Separate from the better-known fintechzoom.com domain
- Limited depth compared with professional terminals
- Predictive or opinion pieces require independent verification
The platform works well for orientation and education. It is less suitable as your sole source when large sums or time-sensitive trades are involved.
Common Mistakes When Following FintechZoom.io Nasdaq Content
Several habits reduce the value of the information:
- Treating the site as if it were the Nasdaq exchange itself
- Ignoring the difference between the Composite and the Nasdaq-100
- Acting on a single chart signal without checking volume or news
- Assuming free data is real-time and exchange-official
- Confusing fintechzoom.io with other similarly named domains
- Overlooking sector concentration risk in tech-heavy indexes
Avoid these by confirming the exact index, noting the timestamp on any quote, and comparing key figures with at least one other reputable source before you decide.
Best Practices for Using the Platform
Follow a simple routine that keeps you informed without over-relying on any single site:
- Bookmark the exact page you trust and type the URL yourself rather than clicking search ads.
- Note which index the chart displays and match it to your investment goal.
- Scan the earnings calendar at the start of each week so large reports do not surprise you.
- Use heatmaps to see whether gains or losses are broad or driven by a few mega-cap names.
- Pair technical readings with fundamental context from company reports or established news outlets.
- Keep position sizes modest when volatility is elevated, especially around major tech earnings.
- Maintain a written checklist of sources you will cross-check before any meaningful decision.
These steps turn scattered data into a clearer picture while limiting the chance of acting on incomplete information.
Practical Examples of Everyday Use
Imagine you hold a Nasdaq-100 ETF and want a quick morning check. You open the fintechzoom.io nasdaq page, note the overnight futures direction, glance at the heatmap, and see that semiconductor names are leading. You then check the earnings calendar and discover two large chipmakers report later in the week. That combination tells you to expect possible swings and to review your risk tolerance before the market opens.
Another scenario: a long-term investor wants to understand why the Composite sometimes lags the Nasdaq-100. By reading the platform’s explainers and comparing the two tables of components, the investor sees that smaller companies and financial stocks in the Composite can dilute pure large-cap tech performance. The insight helps set realistic expectations for different index funds.
Conclusion
FintechZoom.io Nasdaq serves as a convenient hub for charts, index updates, and plain-language context on the technology-focused markets. It is not a substitute for the official Nasdaq exchange, a brokerage, or professional research. When you understand the difference between the Nasdaq Composite and Nasdaq-100, use the available tools as a starting point, and verify important figures elsewhere, the platform can support better awareness of market moves. Markets reward preparation more than speed, so build a simple verification habit and let the data inform rather than dictate your choices.
SEO FAQs
What is fintechzoom.io nasdaq?
It refers to the Nasdaq-focused pages on FintechZoom.io, a financial information site that displays index charts, technical tools, news, and educational content about Nasdaq-listed companies and indexes.
Is FintechZoom.io the same as the Nasdaq exchange?
No. Nasdaq operates the exchange and calculates the official indexes. FintechZoom.io is an independent media and data platform that presents market information.
What is the difference between the Nasdaq Composite and the Nasdaq-100?
The Composite tracks thousands of Nasdaq-listed companies across all sizes and sectors. The Nasdaq-100 tracks about 100 of the largest non-financial companies and is more concentrated in large technology and growth names.
Can I trade stocks directly on fintechzoom.io?
No. The site does not execute trades or hold customer funds. You need a regulated brokerage account to buy or sell securities.
How accurate is the Nasdaq data on the platform?
It is generally useful for directional checks and education, but free feeds can be delayed and should be confirmed with your broker or an official source before any decision.
If you have been searching for quick personal financing in Hong Kong, qlcredit keeps coming up. People want to know whether it is a real licensed lender, how fast money actually arrives, and whether the rates make sense compared with a bank. This guide answers those questions in plain language so you can decide without the usual marketing fog.
QLCredit is the trading name of QL Credit Gain Finance Company Limited, a licensed money lender in Hong Kong. It offers personal loans, debt consolidation, homeowner loans, and SME financing. The company has operated for years under Hong Kong’s Money Lenders Ordinance and is connected to a listed parent group. That background matters, because many “quick cash” brands online have no license at all.
What Is QLCredit and How Does It Work?
QLCredit is not a bank and not a credit bureau. It is a regulated non-bank lender. Borrowers apply online or through the company’s offices, submit identity and income documents, and receive a decision that is often much faster than a traditional bank.
Typical products include:
- Personal loans for emergencies, travel, or cash-flow gaps
- Debt consolidation to roll several debts into one payment
- Homeowner or second-mortgage style loans secured against property
- SME and business financing for smaller companies
Loan amounts commonly go up to HK$2 million or a multiple of monthly salary, whichever is lower. Tenors often range from 6 to 60 months. Advertised rates can start around 10% p.a., but the rate you actually get depends on your profile, collateral, and the product.
The usual application path
Most people follow four steps:
- Fill in a short online form with personal and income details.
- Upload ID, proof of address, and proof of income.
- The lender reviews the file (sometimes within hours, sometimes 1–3 days).
- If approved, you sign the loan documents and funds are disbursed to your bank account.
Speed is the main selling point. Banks can take weeks. A licensed money lender can move faster because the underwriting rules are different, though you usually pay for that speed with a higher interest rate.
Is QLCredit Legit and Regulated?
Yes. QL Credit Gain Finance Company Limited holds a money lender licence under Hong Kong’s Money Lenders Ordinance (Cap. 163). That law requires clear interest disclosure, proper contracts, and borrower protections. The company has a registered office in Wan Chai and a publicly documented history going back many years, including earlier names such as Hong Kong Credit Gain Finance.
A licence does not guarantee the cheapest deal or perfect customer service. It does mean the firm is not an anonymous app that can disappear overnight. Always confirm the current licence number on the official Hong Kong Companies Registry / money lenders register before you sign anything.
| Check | What to look for | Why it matters |
|---|---|---|
| Licence | Valid money lender licence (Cap. 163) | Confirms legal right to lend in Hong Kong |
| Company name | QL Credit Gain Finance Company Limited | Matches official records, not a lookalike brand |
| Address | Documented Wan Chai / Central Plaza office | Physical presence, not only a website |
| Parent link | Connection to listed financial group | Extra layer of accountability |
| Contract | Written terms, APR, fees, repayment schedule | Required by law; read before signing |
QLCredit vs Traditional Banks
People compare the two because they solve similar problems in different ways.
| Feature | QLCredit (licensed money lender) | Typical bank personal loan |
|---|---|---|
| Approval speed | Often same day to a few days | Days to several weeks |
| Credit flexibility | More room for imperfect files | Stricter score and income rules |
| Interest cost | Usually higher | Usually lower for strong profiles |
| Process | Mostly digital plus documents | Branch + online, more paperwork |
| Best use | Urgent cash or consolidation | Planned, lower-cost borrowing |
| Regulation | Money Lenders Ordinance | Banking Ordinance + HKMA |
If your credit file is clean and you can wait, a bank is often cheaper. If you need funds quickly or a bank already said no, a licensed money lender can be the practical option—provided you understand the total cost.
Pros and Cons of Using QLCredit
Pros
- Faster decisions than most banks
- Licensed and publicly identifiable company
- Multiple product types (personal, property-backed, SME)
- Flexible underwriting compared with big banks
- Clear legal framework for contracts and collection
Cons
- Interest and fees are often higher than bank loans
- Approval is not guaranteed; income and documents still matter
- Shorter tenors can mean larger monthly payments
- Customer experience varies; some borrowers report slow follow-up
- Easy access can tempt people to borrow more than they can repay
Speed is useful. It is not free.
Common Mistakes People Make with QLCredit
Borrowers run into trouble when they treat a money lender like a credit card they never have to think about.
- Applying without calculating the full monthly payment, including fees
- Ignoring the APR and focusing only on the advertised “from 10%”
- Using a short-term loan for a long-term problem
- Submitting incomplete documents and then blaming the lender for delays
- Signing before reading early-repayment or penalty clauses
- Stacking a new loan on top of existing high-interest debt
A loan that arrives tomorrow still has to be repaid for months or years. That is the part many people skip.
Best Practices Before You Apply
Do these five things first:
- Confirm the current licence on the official Hong Kong register.
- List every existing debt and the real monthly surplus you can afford.
- Ask for a written quotation that shows APR, fees, and total repayable amount.
- Compare at least one bank offer and one other licensed money lender.
- Keep copies of every document you upload and every contract you sign.
If the numbers only work if nothing goes wrong in your income for the next two years, the loan is too large.
Practical example
Suppose you need HK$80,000 for a medical bill. A bank quote at 6% over 36 months might cost far less in interest than a money-lender quote at 12–18% over 24 months. The money-lender option can still be rational if the bank declines you or if waiting two weeks is not possible. The rational choice is the one where you can still eat and pay rent after the installment leaves your account.
Who QLCredit Fits Best
QLCredit tends to make sense for:
- Hong Kong residents who need funds faster than a bank can move
- Borrowers with income but imperfect or thin credit files
- Homeowners who can use property as security for a better rate
- Small business owners needing short-to-medium working capital
- People consolidating several expensive short-term debts into one payment
It is a weaker fit if you qualify easily for a cheap bank loan and have time to wait.
Conclusion
QLCredit is a real, licensed Hong Kong money lender, not a mystery app. It exists to fill the gap banks leave: faster cash, more flexible underwriting, and products that include personal loans and property-backed financing. The trade-off is cost. Read the contract, confirm the licence, and only borrow an amount your monthly budget can absorb without drama. That is how you use a service like this without turning a short-term problem into a long-term one.
5 SEO FAQs
What is QLCredit?
QLCredit is the brand name of QL Credit Gain Finance Company Limited, a licensed money lender in Hong Kong that offers personal loans, debt consolidation, homeowner loans, and SME financing.
Is QLCredit legit?
Yes. It operates under Hong Kong’s Money Lenders Ordinance with a registered company and a documented office. Always verify the current licence on the official register before applying.
How fast can I get money from QLCredit?
Many applications move faster than banks—sometimes within 24 hours to a few days—once documents are complete. Exact timing depends on the product and your file.
What interest rate does QLCredit charge?
Advertised rates can start around 10% p.a., but the rate you receive depends on loan type, security, income, and credit profile. Always ask for the APR and total repayable amount in writing.
Is QLCredit better than a bank loan?
Not always. Banks are usually cheaper if you qualify and can wait. QLCredit is more useful when you need speed or a bank has already declined you.
People keep typing coyyn into search bars because the name shows up everywhere at once: finance blogs, wallet reviews, gig-economy posts, and “what is this platform?” threads. The short version is this: Coyyn is used as a brand name for digital-finance content and tools that sit at the intersection of payments, freelance work, and crypto-adjacent services. The longer version matters more, because the same name is used in different ways depending on the site you land on.
If you are a freelancer waiting on a client payment, a small business looking at cross-border transfers, or someone trying to understand digital wallets without drowning in jargon, you need a clear map—not hype. This guide explains what the name usually refers to, how the claimed features work in plain language, where the value can be real, and where you should slow down and verify.
What Coyyn Usually Refers To
Coyyn most often appears as:
- A finance education site covering banking, capital, crypto, and the gig economy
- A digital wallet / payments concept aimed at freelancers and small teams
- A branding label for blockchain-backed transfers, multi-currency balances, and smart-contract style automation
There is no single official dictionary meaning. In practice, searchers treat it as a digital-finance brand. That is why results mix “about us” pages, payment-feature lists, and skeptical reviews in the same results page.
A simple definition for featured snippets
Coyyn is a digital-finance brand name used for platforms and content that help people manage online money, freelance payments, and crypto-related tools. It is not a traditional bank. Treat every product claim as something to verify against licenses, custody details, and withdrawal tests.
That definition keeps expectations honest. A blog that explains digital banking is not the same thing as a licensed bank. A wallet that supports crypto is not automatically a regulated brokerage.
Why the Name Is Getting So Much Attention
Three forces push the searches:
- Gig work went global. Freelancers want faster payouts and fewer middlemen.
- Digital wallets mixed fiat and crypto. People want one dashboard instead of five apps.
- Brand-style names with double letters travel well in search and social.
Add those together and a short, unusual name becomes a magnet for “is this legit?” queries.
Search intent behind coyyn
Most people arriving on this topic want one of four answers:
- What is it?
- Is it safe?
- Can I get paid or send money with it?
- How does it compare with banks, PayPal, Wise, or major crypto wallets?
Good content answers those in that order.
How Coyyn-Style Platforms Typically Work
Even when product details differ by site, the workflow is usually the same.
Step-by-step user path
- Create an account and complete identity checks (KYC).
- Link a bank card, transfer, or crypto deposit.
- Hold balances in fiat, stablecoins, or major coins.
- Send a peer-to-peer payment or invoice a client.
- Convert currencies if needed.
- Withdraw to a bank or external wallet.
If any of those steps is missing, slow, or poorly documented, that is a red flag.
Features people expect to see
| Feature area | What it is supposed to do | What you should verify |
|---|---|---|
| Digital wallet | Store fiat and crypto in one place | Who holds the keys? Hot vs cold storage? |
| P2P payments | Send money to freelancers or vendors | Fees, limits, settlement time |
| Multi-currency | Hold USD, EUR, and major coins | Real conversion rates vs hidden spreads |
| Smart contracts | Auto-pay when work is delivered | Audit status and who can pause a contract |
| Analytics | Show cash flow and forecasts | Is it insight or generic charts? |
| Compliance | KYC, AML, GDPR-style privacy | Named legal entity and regulator |
A table like this is more useful than a feature dump. Features only matter if custody, fees, and withdrawals are real.
Coyyn and the Gig Economy
This is where the brand story is strongest. Freelancers lose money to platform commissions, currency conversion, and delayed payouts. A tool that cuts those frictions is valuable—if it works.
Practical example
A designer in Nairobi invoices a client in Berlin. On a traditional stack, the invoice waits on a marketplace, then a card processor, then a local bank. Fees stack. Settlement can take days.
A Coyyn-style flow claims the opposite: invoice, on-chain or wallet payment, conversion to a stablecoin or local currency, withdrawal. The promise is speed and lower fees. The test is whether the withdrawal actually lands.
Who it is built for
- Independent designers, developers, writers, and consultants
- Small agencies paying remote contractors
- Digital creators collecting international tips or retainers
- Founders who need a simple multi-currency dashboard
It is a weaker fit for people who only need a local checking account and never send money abroad.
Pros and Cons
No platform in this category is all upside. Use this snapshot before you move real money.
| Pros | Cons |
|---|---|
| One place for invoices, balances, and transfers | Brand information is inconsistent across sites |
| Potential lower fees than card-heavy marketplaces | Regulatory status is not always easy to confirm |
| Useful for cross-border freelance work | Crypto volatility can hit unpaid invoices |
| Dashboard thinking beats scattered apps | Support quality varies with new fintech brands |
| Educational content can demystify digital finance | Some coverage of the name is thin or recycled |
The honest take: the idea is useful. The execution has to be proven per product, not assumed from a homepage.
Common Mistakes People Make With Coyyn and Similar Tools
These errors show up again and again.
Treating a content site as a bank
A blog about digital banking is not a deposit account. If you cannot find the licensed entity, do not deposit.
Skipping the withdrawal test
Always send a small amount out before you send a large amount in. Platforms fail at the exit more often than the entrance.
Ignoring the spread
“Zero fee” often hides a worse exchange rate. Compare the final amount received, not the headline fee.
Mixing long-term savings with a hot wallet
Money you cannot afford to lose does not belong in an experimental app. Keep a separate cold or bank reserve.
Believing every traffic spike equals trust
High search volume can come from curiosity, ads, or lookalike domains. Traffic is not a security audit.
Best Practices Before You Use a Coyyn-Style Platform
Follow this checklist.
- Identify the legal company name, country, and directors.
- Confirm licenses on the regulator’s own website, not a badge image.
- Read the custody model: custodial vs self-custody.
- Check third-party audits if crypto is involved.
- Test deposit, conversion, and withdrawal with a tiny amount.
- Turn on 2FA and withdrawal allowlists.
- Keep tax records. Cross-border freelance income still needs reporting.
- Separate operating cash from savings.
A simple decision framework
| Your situation | Better first move |
|---|---|
| You only need local everyday banking | Stay with a licensed bank or credit union |
| You invoice overseas clients monthly | Compare Wise, Payoneer, and any Coyyn-style wallet side by side |
| You already hold crypto | Use a well-known exchange plus self-custody for long-term coins |
| You want education, not a product | Read multiple independent sources, not one branded hub |
| You cannot verify the company | Do not fund the account |
Frameworks beat vibes. If a platform cannot survive that table, wait.
How Coyyn Compares With Familiar Options
Think in jobs-to-be-done, not logos.
- Banks win on deposit insurance and familiarity.
- Wise-style services win on transparent FX for fiat.
- Major exchanges win on liquidity and brand history.
- Niche fintech wallets win only if they are cheaper, faster, or better for a specific freelance workflow.
Coyyn, as a category name, is trying to sit in that last box. That is a crowded box. Differentiation has to be operational, not poetic.
Security and Trust Signals That Actually Matter
Ignore glow words like “revolutionary.” Look for:
- A real registered business
- Named leadership
- Clear fee schedule
- Published support hours
- Independent security review
- Proof that other users can withdraw
- No pressure to recruit or lock funds
If a page leans hard on “AI + blockchain + smart contracts” and light on company details, treat it as marketing until proven otherwise.
Conclusion
Coyyn is best understood as a digital-finance brand sitting between education, freelance payments, and crypto-enabled wallets. The search interest is real because remote work and multi-currency money are real. The risk is also real, because the same short name is attached to different claims depending on which page you open.
Use the name as a starting point, not a finish line. Define the job you need done—get paid, convert currency, store assets, or learn the basics—then judge the specific product against licenses, custody, fees, and a live withdrawal test. That habit will serve you on this brand and the next one that appears with a clever double-letter name.
FAQs
What is Coyyn?
Coyyn is a digital-finance brand name used for websites and tools related to online payments, freelance money management, and crypto-adjacent wallets. It is not a traditional bank.
Is Coyyn a cryptocurrency?
Not by default. Some pages describe a token or crypto wallet features, but the name itself is a brand. Always check whether a specific product lists a real asset, contract address, and custody model.
Is Coyyn safe to use?
Safety depends on the exact company behind the product you open. Look for a legal entity, regulator listing, audits, and a successful small withdrawal before you trust it with meaningful funds.
Who should consider a Coyyn-style platform?
Freelancers and small teams that get paid across borders may benefit if fees and settlement beat their current stack. People who only need local banking usually will not.
How do I start without taking a big risk?
Create an account if you must, complete verification, move a tiny test amount through deposit, conversion, and withdrawal, then decide. Never skip the exit test.

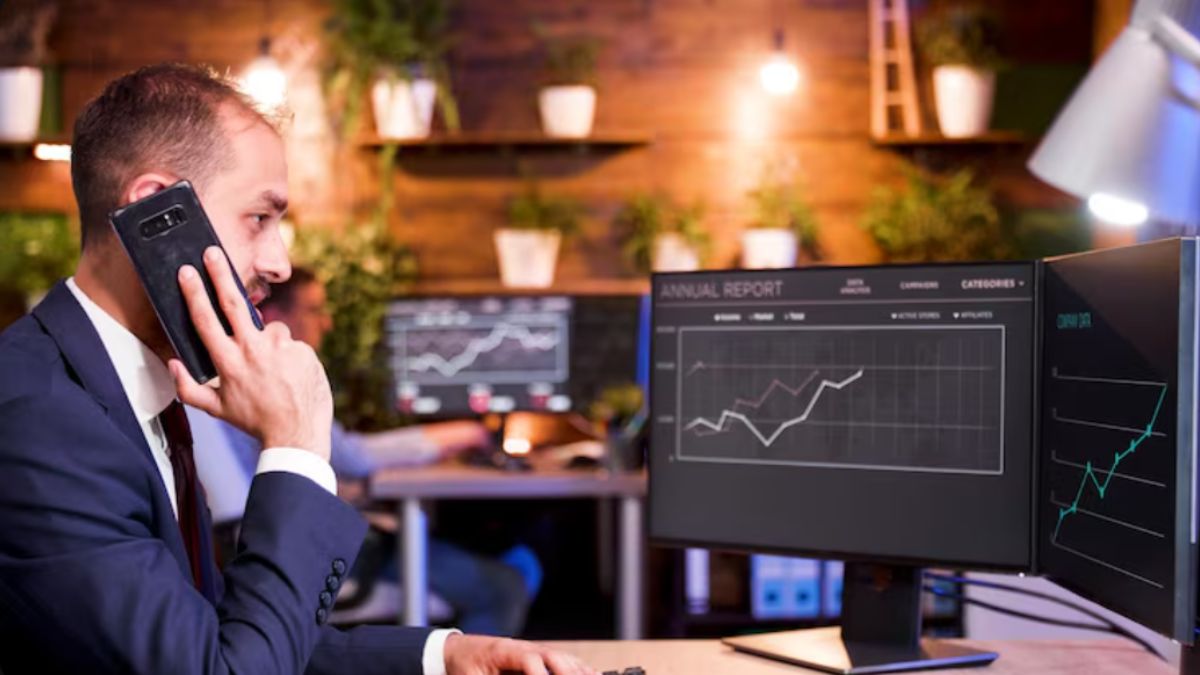
You may struggle to pick a trading service that fits your needs and budget. Fees, security, and market access vary a lot between providers. This post lists the key features to compare and explains what each one means.
Read on.
Costs and Fees
Costs and fees play a big role in choosing a trading service. You should check for commissions, account charges, and any hidden costs before you start trading.
Commissions and spreads
Brokers charge commissions per trade or widen the spread between buy and sell prices. Low trading fees help keep returns higher. Compare fee structures across trading platforms and brokerage accounts.
Spreads affect order execution and slippage. Tight spreads suit active traders and forex or crypto access. Next, compare account fees and hidden charges.
Account fees and hidden charges
Account fees can cut into returns. Inspect fees and commissions for trades and account maintenance. Check for inactivity charges, withdrawal costs, and transfer fees. Use fee tables from each brokerage account to compare charges across account types and trading platforms.
Ask about hidden charges such as market data fees or platform access fees. Compare fee schedules and sample trade costs before you fund an account. Now check margin financing rates to see borrowing costs.
Margin financing rates
Margin financing rates show the cost to borrow money for trades. Brokers set these rates as an annual percentage. Compare rates across trading platforms and brokerage accounts. High rates raise trading fees and cut profit margins.
Some brokerages charge tiered rates by loan size or account type. Lower rates suit active traders who use leverage and multiple asset classes. Check fees and commissions and read the terms on margin.
Safety and Regulation
Safety and regulation are key when choosing a trading service. You want to know if the platform follows rules and protects your money.
Regulatory approvals and licenses
Regulatory approvals and licenses show if a trading service meets legal standards. They ensure that the company follows rules set by financial authorities. For example, firms regulated by the SEC or CFTC offer more safety for your funds.
Check if the broker has licenses in your area. If they are licensed, it often means they provide better protection for investors. Look for services with clear regulatory information; this adds trust to their operations.
Fund protection measures
Fund protection measures are essential for traders. They provide a safety net for your money. Many trading services offer insurance to protect funds in case of company failure. This helps keep your investments secure.
Some firms use segregation accounts for client funds. These separate accounts ensure that client assets do not mix with the firm’s own money. Regular audits verify that these protections work as intended.
Choose a trading platform with strong fund protection options to safeguard your investment effectively.
Tradable Assets and Market Access
You need to know what assets you can trade. Check if the service offers stocks, forex, crypto, or other options that meet your needs.
Availability of desired markets (stocks, forex, crypto, etc.)
Finding a trading service that offers your desired markets is key. Many traders want access to stocks, forex, or cryptocurrencies. Not all platforms provide the same range of assets.
Some focus on traditional stocks while others specialize in digital currencies.
Check the types of assets available. A good service will allow you to trade across different markets. This helps diversify your investments and spread risk. Look for options like forex pairs or popular cryptocurrencies if they interest you.
Access to various markets can enhance your trading experience and opportunities for profit.
Range of order types (stop-loss, limit orders, etc.)
Trading services offer various order types to help manage trades. These orders can protect investments and set limits on buying or selling.
- A stop-loss order automatically sells a stock when its price drops to a certain level. This helps limit losses if the trade goes against you.
- A limit order buys or sells a stock at a specified price or better. This allows you to control the price you pay or receive.
- A market order buys or sells a stock immediately at the current market price. Speed is key with this type of order.
- A trailing stop order adjusts as the stock price moves up. It locks in profits while allowing for gains to continue until the price falls back to the set level.
- A fill-or-kill order executes immediately at your specified price. If it cannot be filled right away, it cancels completely.
- An all-or-none order requires that all shares be sold or none at all. This ensures that you do not end up with partial fills.
Accessing these different order types enhances your trading strategy. Next, consider safety and regulation when choosing a trading service.
Platform Usability and Tools
A good trading platform should be easy to use. It should have helpful tools for charts and indicators to support your trading decisions.
User-friendly interface and navigation
A user-friendly interface makes trading easier. It allows traders to find what they need quickly. Simple menus and clear buttons help users navigate the platform with ease. Good platforms offer quick access to important features like charts, orders, and accounts.
Easy navigation helps prevent mistakes during trades. If a trader can easily see their balances or order types, they can make better decisions fast. A clean layout improves focus on trading activities.
This feature is key for both new and experienced traders alike, ensuring that all users feel confident using the service.
Charting tools and technical indicators
User-friendly interfaces lead to better trading experiences. Charting tools and technical indicators also play a key role in this. Traders use these tools to analyze price movements.
They can spot trends and make informed choices.
Technical indicators help traders see hidden patterns in the market. Examples include moving averages, MACD, and RSI. These indicators guide buyers and sellers on when to enter or exit trades.
Quality charting software allows easy customization too, so users can set it up based on their preferences. Access to such features adds great value for traders looking for success in their strategies.
Performance and Customer Support
The speed of trade execution is crucial. Fast trades can make a big difference in profits. Good customer support helps you when issues arise. You want to reach out easily and get quick answers.
Execution speed for trades
Execution speed impacts your trading success. Faster execution means trades complete quickly, which is crucial in volatile markets. Delays can cost you money. Many trading platforms offer quick order fills, but speeds can vary.
Look for platforms with low latency technology. This tech reduces delays during busy times or sudden market changes. Efficient execution helps you buy at the right moment and sell before prices drop.
Trade confidently knowing your orders will execute swiftly and accurately rather than lagging behind the market’s movements.
Accessibility of customer service
Customer service should be easy to reach. Look for services with multiple contact options, like phone, email, and live chat. Some trading platforms offer 24/7 support while others have limited hours.
Fast response times are crucial too; you want help when needed.
Good customer support can make a big difference during trades. A real person on the other side can ease any worries about your investments. Easy access to assistance builds trust in your trading platform’s reliability.
Next, consider the performance and execution speed for trades as another key feature to compare.
Conclusion
Choosing a trading service takes care and thought. Compare costs, safety, and the types of assets available. Look for easy-to-use platforms with good support. Pay attention to fees and execution speed too.
Make an informed choice that fits your needs.
-
 NEWS1 year ago
Historical Churches in Manila
-
 TOPIC3 months ago
Unveiling AvTub: Your Ultimate Guide to the Best AV Content
-
 TOPIC1 year ago
Symbols of Hope: The 15th Belenismo sa Tarlac
-
 TOPIC1 year ago
RIZAL at 160: a Filipino Feat in Britain
-
 TOPIC1 year ago
Simbang Gabi and Kakanin
-
 TOPIC2 months ago
Understanding Fascisterne: Origins and Ideological Roots
-
 TOPIC1 year ago
“The Journey Beyond Fashion” – Ditta Sandico
-
 NEWS4 months ago
What Caused Delta Flight DL275 to Diverted LAX? A Detailed Breakdown