TOPIC
How Much Should You Keep in a Savings Account Before Investing or Paying Debt?

Money decisions feel urgent when every dollar has a clear job each month. You may want to invest before prices rise further, pay down debt before interest builds, and keep enough cash to avoid stress when life changes. The right answer depends on income stability, debt cost, family needs, and how soon you may need the money.
Start With Stability Before Growth
Before choosing between investing and debt repayment, build a basic safety layer. This is the cash you can reach quickly when a car repair, vet bill, medical cost, job gap, or urgent trip appears unexpectedly. It is not meant to cover holidays, school supplies, property taxes, or planned insurance renewals because those costs need their own budget line.
A useful first target is one month of essential expenses. That means rent or mortgage payments, utilities, groceries, transportation, insurance, minimum debt payments, and medication. This starter reserve can stop one surprise bill from becoming a larger problem.
Once that first layer exists, you can decide whether to grow it further, invest, or accelerate debt repayment. If you are reviewing options for savings accounts in Canada, a practical choice such as high-interest savings with Innovation Federal CU can keep cash accessible while giving idle money a chance to earn more than in a basic transaction account.
How Much Cash Is Enough?
Many households use three to six months of essential expenses as a practical emergency fund target. Three months may be enough for a person with stable employment, two incomes in the home, strong insurance coverage, and low fixed costs. Six months may suit self-employed workers, commission earners, caregivers, newcomers, single-income families, or anyone whose next job could take longer to find.
The key is measuring essentials, not your normal lifestyle. Restaurant meals, streaming extras, vacations, shopping, and nonurgent subscriptions can be reduced during a crisis. Your emergency number should focus on the bills that must be paid even when income drops.
A larger reserve is not always better. Keeping too much cash can slow retirement contributions, delay debt freedom, and reduce long-term growth because cash usually has lower expected returns than diversified investments. Cash protects you from shocks, but it is not designed to do every financial job.
Use Your Risk Level as the Guide
A good cash target starts with honest questions. How secure is your income? How quickly could you replace it? Do you support children, parents, or a partner? Are you a homeowner with repair risk, or a renter with fewer surprise maintenance costs?
If the answers point to higher risk, hold more cash before investing aggressively. If the answers point to lower risk, you may be comfortable keeping a leaner reserve and directing extra money to debt or investments. The best number lets you sleep while still moving forward.
When Debt Should Come First
Debt cost matters more than debt size. A small credit card balance at a high-interest rate can be more damaging than a larger student loan or mortgage with a much lower rate. Paying the highest interest debt first reduces total interest and shortens the debt-free path.
Start by making every required minimum payment on time. Late fees, penalty rates, and credit score damage can make a bad situation worse. After that, direct extra money toward the debt with the highest rate while keeping your starter emergency reserve intact.
There is one important exception. If you have no cash cushion at all, send some money to savings before you attack debt with full force. Otherwise, the next emergency may push you back onto the same credit card you just paid down.
Think in After Tax Returns
Paying high-interest debt can be similar to earning a guaranteed return. If a card charges a very high rate, every dollar you pay down saves future interest with no market risk. An investment would need to earn more after fees, taxes, and volatility to beat that outcome.
This does not mean every debt must disappear before investing. Low-interest debt, employer-matched retirement plans, and tax-advantaged accounts can change the math. The point is to compare the cost of debt with the realistic return of the alternative, not with a hopeful best-case scenario.
When Investing Can Start Earlier
Investing may make sense once you have a starter reserve, your high-interest debt is under control, and your monthly cash flow is stable. Waiting until every loan is gone can delay years of compounding, especially for people with low-rate student loans, car loans, or mortgages. The earlier money is invested, the more time it has to ride through market cycles.
In Canada, many people begin with a TFSA because qualified withdrawals are generally tax-free, and contribution room can be reused in a future year after a withdrawal. RRSPs may also be useful, especially when contributions reduce taxable income and the investor expects a lower tax rate in retirement.
The middle path is often strongest. You can invest a fixed amount each month, pay extra toward costly debt, and continue growing cash toward your target.
Choose the Right Place for Your Cash
Emergency money should be liquid, separate, and easy to understand. It should not be locked in a long-term investment, tied to market prices, or mixed with everyday spending. When comparing banks, online providers, and the best credit unions for your day-to-day cash, look beyond the headline yield and review access, transfer times, fees, insurance coverage, and service quality.
Deposit protection also matters. Eligible deposits at CDIC member institutions are protected up to set limits by category, while many credit unions operate under provincial deposit protection systems. Before holding a large balance, check the coverage for your institution and account type.
Why Fees Matter
A no-fee savings account can be useful when your balance is still small because monthly charges can erase interest quickly. Transfer limits, withdrawal fees, minimum balance rules, and promotional rates deserve attention too. A high advertised rate is less attractive if you cannot access the money easily or if conditions reduce the real benefit.
Separate accounts can also improve behavior. One account can hold emergency money, another can hold short-term goals, and investments can remain in registered or non registered accounts.
A Practical Order of Operations
A simple sequence can remove much of the confusion:
- Cover basic monthly bills and make all minimum debt payments.
- Build a starter cash reserve of one month of essentials.
- Attack high-interest debt while continuing small automatic savings.
- Expand your emergency fund toward a target that matches your risk level.
- Once the cushion is strong enough, send extra money to investments, lower-rate debt, or planned goals such as a home purchase, education, travel, or business costs.
- Review the plan whenever your income, rent, mortgage, family size, or job situation changes.
This order is not rigid. Someone with unstable work may prioritize cash for longer. Someone with expensive debt may keep only a starter reserve until the worst balances are gone. Someone with an employer match may invest enough to capture that benefit while still paying debt.
The Number Is Personal
The right amount to keep in cash is the amount that protects you from predictable financial stress without trapping too much money on the sidelines. For many people, that means one month of essentials before serious debt payoff, three to six months before heavier investing, and a larger cushion when income is uncertain.
Self managed home care packages have become an increasingly popular option for individuals who wish to maintain control over their care services. These packages empower recipients to personalise their care according to their unique needs and preferences, offering a level of autonomy that traditional care options may not provide. By opting for self managed home care packages, clients can tailor their care arrangements with greater flexibility.
What Are Self Managed Home Care Packages?
Self managed home care packages are government-funded programs that allocate resources directly to individuals, enabling them to coordinate and manage their own home care services. Unlike fully managed packages, where a service provider administers the care plan, self management allows recipients to choose their preferred carers, schedules, and services, promoting independence and personalised support.
Benefits of Self Management
One of the key advantages of self managed home care packages is the significant degree of control granted to the care recipient. This control helps ensure that services align closely with personal needs and expectations. Additionally, self management can often lead to greater satisfaction with care quality due to the ability to select trusted providers and customise care elements.
Moreover, self management encourages active participation in budgeting and financial decisions. This involvement can foster a better understanding of how funds are allocated and spent, contributing to more effective utilisation of resources.
Who Is Eligible?
Eligibility for self managed home care packages typically mirrors that of standard home care packages. Participants must be assessed for need through an official assessment process, often conducted by local health authorities or aged care assessment teams. Once approved, individuals can decide whether to take a self management route based on their capability and desire to oversee their care arrangements.
Getting Started with Self Managed Packages
Initiating a self managed home care package begins with an assessment and allocation of a funding package. Afterward, recipients work closely with care advisors or coordinators to understand their responsibilities, legal obligations, and financial management requirements. Training and support are often provided to assist clients in effective package management.
Responsibilities Under Self Management
When self managing home care packages, clients assume responsibilities that include budgeting, record keeping, and ensuring compliance with regulatory standards. They must also organise and coordinate service providers, negotiate service agreements, and ensure that all activities align with the care plan goals.
These responsibilities demand a certain level of organisational skill and commitment. However, for many, the benefits of personalised control outweigh these demands.
Challenges to Consider
Despite the advantages, self management may not suit everyone. Some individuals may find the administrative aspects complex or overwhelming. There is also a necessity to understand legal and financial compliance, which can require additional support or training.
In addition, managing multiple service providers and maintaining consistent care quality requires active oversight. Without adequate support, there is a risk of inconsistency or gaps in care provision.
Support and Resources Available
To address potential challenges, numerous support resources are available to those managing their care packages. These include advisory services, financial management tools, and training programs. Organizations like Homecare My Way provide specialised assistance to ensure clients can confidently manage their packages effectively.
Financial Management and Oversight
Financial accountability is a critical component of self managed home care packages. Recipients must prepare budgets, track expenditures, and ensure funds are spent according to the approved care plan. Transparent record keeping is essential to satisfy regulatory requirements and to monitor the sufficiency of allocated funds.
Some clients choose to engage financial consultants or administrators to assist with these tasks, reducing administrative burden and mitigating risks.
Legal and Regulatory Compliance
Compliance with legal and regulatory guidelines is mandatory when self managing care packages. Clients must adhere to national aged care standards, privacy laws, and workplace health and safety regulations when employing care workers or contractors.
Understanding these requirements helps to avoid breaches that could jeopardise the funding package or lead to legal consequences.
Choosing Service Providers
A cornerstone of self management is the freedom to select and engage service providers. This selection process involves evaluating providers based on qualifications, experience, reliability, and compatibility with the client’s needs.
Clients should undertake thorough research and potentially trial services before committing to long-term arrangements. Strong communication and clear expectations help foster successful partnerships.
Personalising Care Plans
With self management, care plans become highly personalised documents reflecting the preferences and goals of the recipient. This personalisation covers a wide range of services, including personal care, household assistance, social support, and specialised therapies.
Periodic reviews are essential to ensure that the care plan remains relevant and effective, adapting to any changing needs or circumstances.
Maintaining Quality of Care
While self managing care packages grants autonomy, maintaining high-quality care remains paramount. Continuous monitoring of service delivery, feedback mechanisms, and open communication with care providers contribute to sustaining standards.
Issues should be addressed promptly to preserve the wellbeing and satisfaction of the recipient.
Transitions from Other Care Options
Individuals transitioning from provider-managed or combined care packages to self management should prepare for changes in responsibility and oversight. This transition period often involves comprehensive support to build confidence in managing all facets of care independently.
Conclusion
Self managed home care packages present an empowering choice for individuals seeking personalised, flexible, and autonomous care solutions. While they require an increased level of administration and responsibility, the benefits of tailored services and client control are considerable. With proper support and resources, self managing care packages can enhance quality of life and satisfaction for many care recipients.
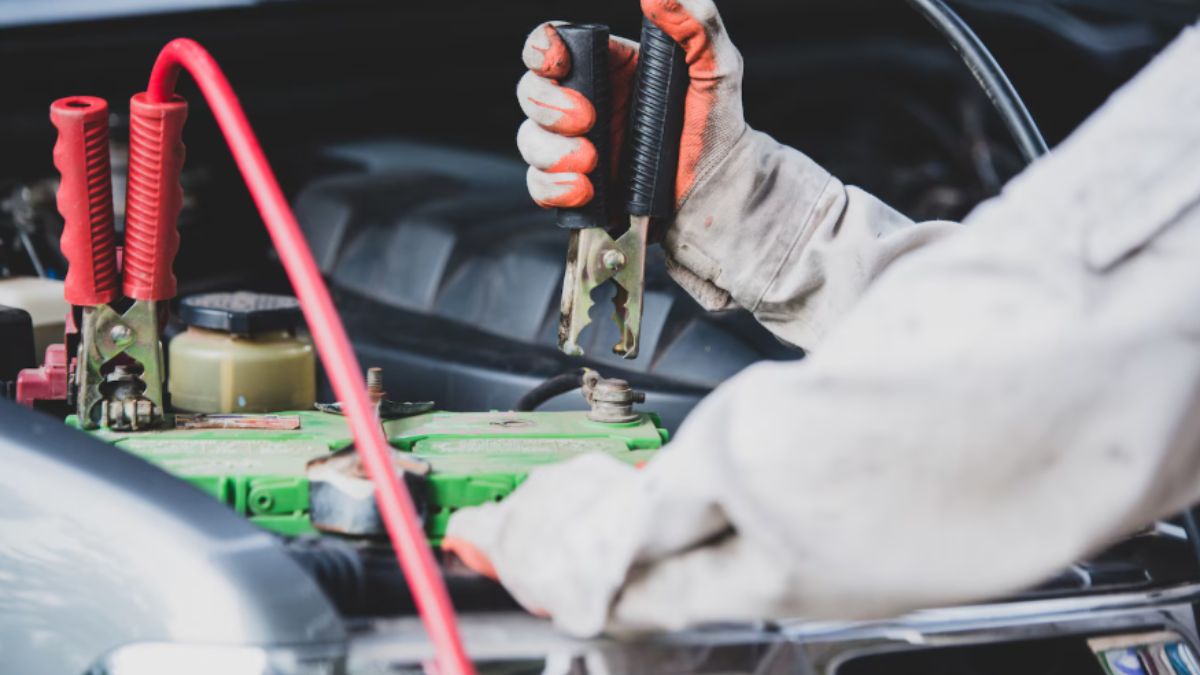
There’s something about the Australian climate that feels like it’s in a long-term argument with anything electronic. Phones overheat. Drones lose power faster. Even chargers feel warm before they’re supposed to. And when it comes to 4s lipo batteries, the heat isn’t just annoying—it’s kind of a slow, invisible thief, stealing lifespan and stealing performance and sometimes stealing whole batteries before they’ve even lived a decent life.
Most hobbyists eventually learn that LiPos don’t behave the same way in Australia as they might in more incredible places. The afternoon sun alone can turn a perfect pack into a puffy, reluctant mess. Not ideal. Not cheap either. Especially when you’re running multiple drones, RC cars, or whatever else your weekend obsession happens to be.
So let’s talk about real, practical ways to make 4s lipo batteries last longer here. Not generic “store in a cool place” tips — the kind of stuff people figure out after a few expensive mistakes, some swollen packs, and maybe one too many smoky charging scares.
The Heat Is the Enemy (But You Probably Know That Already)
LiPos are dramatic. They like a narrow comfort zone.
Too cold? They act lazy.
Too hot? They age twice as fast. Sometimes three times as fast if the Aussie summer decides to show off.
If you’ve ever left 4s lipo batteries in your car boot on a 35-degree day, you know what I’m talking about. You open the boot and suddenly feel like you’re checking on something fragile that shouldn’t be sitting in an oven. And honestly? You kind of are.
Give Them a Break Between Runs
A weird thing happens when you’re having fun with drones or RC cars. You forget the batteries are quietly suffering while you’re enjoying yourself. You burn through one pack, then another, then another. They get warm. Then hotter. And instead of letting them cool properly, you chuck them straight back on the charger.
This is one of the fastest ways to kill 4S LiPo batteries.
Let them rest. Really rest.
Not just “warm to the touch, but you think it’s fine” rest.
Cool down completely before charging again. It feels slow and tedious, but it extends their lifespan in ways you can’t fully appreciate until you compare old habits to new ones.
Charging in Hot Weather — A Little Extra Care Please
A lot of people charge their batteries in garages or sheds, probably because it feels like the sensible thing to do. Keep the stuff with potential fire risk away from the central part of the house. Fair enough.
The problem is, garages hit insane temperatures during Aussie summers. I’ve seen chargers sitting on metal shelving units that felt hotter than the battery itself.
4s lipo batteries don’t love that. They don’t even tolerate it.
Charging them in a cooler spot — maybe inside, near a fan, or in an air-conditioned room — isn’t overly cautious. It’s being practical. And smart. And probably saving you hundreds over time.
The Magic of Storage Voltage (Seriously, It Matters)
Every LiPo guide ever mentions storage voltage, but it usually sounds like one of those things people repeat because they’re supposed to. But here’s the thing: it really does matter here in Australia.
Leaving 4s lipo batteries fully charged while they’re sitting in a room that hits 30+ degrees?
That’s like leaving a carton of milk in the sun and hoping for the best. They deteriorate from the inside out.
Keep them at storage voltage — around 3.8V per cell — whenever you’re not actively flying or driving.
Your future self (and wallet) will thank you.
Cooling Bags, Shade, and Other Not-So-Fancy Tricks
You don’t need high-tech battery cooling solutions. Simple tricks work great.
- Store your packs in the shade at flying fields.
• Toss a few cool packs (wrapped, not touching directly) in your LiPo bag.
• Keep your bag under a table instead of out on the dirt or pavement.
Little things. But each one slows the heating cycle. And slowing down the heat is half the battle in keeping 4s lipo batteries alive longer.
Watch for Swelling — The Silent Warning Sign
Swelling doesn’t always happen dramatically. Sometimes it’s subtle. A slight bulge. A soft corner. A feeling like the pack isn’t as “tight” as it used to be.
When swelling starts, it’s usually because the cells have been stressed repeatedly — often by heat, over-discharging, or rushing the charge cycle.
Once swelling is noticeable, 4S lipo batteries are basically telling you, “Hey, I’m not safe anymore.”
Don’t push them. Don’t try to squeeze extra cycles out of it. Retire them safely.
Avoid Full Discharge (Yes, Even When You’re Having Fun)
Going below 3.5V per cell under load is risky. Going lower than that?
Well, that’s how batteries end up in the bin far sooner than they should.
Australia’s heat amplifies voltage sag, making it easier to dip too low without realising. Keep an eye on your telemetry or voltage alarms. If you don’t have one, get one. Cheap investment compared to the cost of new 4S LiPo batteries.
Good Chargers Make a Big Difference
A charger is not just a charger. Some balance terribly. Some overheat. Some drift over time. And in hot climates, that drift can be the final straw.
A quality charger protects your packs from subtle wear.
It keeps cells aligned. Prevents overcharging. Avoids heat spikes.
Basically, it gives your 4s lipo batteries a fairer shot at a long life.
Be Realistic — Aussie Conditions Wear Things Out Faster
We’re not flying in Canada. Or Norway. Or anywhere cool.
We’re flying in harsh sunlight, hot dirt, high humidity, coastal wind, dry inland heat — sometimes all in the same week.
Understanding that Australia is more stringent with 4S LiPo batteries than many other places helps you adjust your habits. You don’t need perfection. Just awareness. Minor adjustments, one at a time, that add up to longer-lasting packs.
Final Thought… Or Maybe Just a Quiet Reminder
LiPos don’t last forever. They’re not meant to. But with a bit of patience, some cooling breaks, a good charger, and a habit of avoiding full charges on hot days, you can easily double their lifespan.
If you rely on 4S LiPo batteries from RC Battery for drones, RC cars, boats, or FPV setups, treat them like they’re slightly picky house guests. They behave better when you respect their comfort zone.
It starts early. Way earlier than most buyers think. We’ve watched enough property stories unfold to notice the same pattern every time. People spend months comparing suburbs, loan rates and floor plans, then leave the legal side until the contract is sitting in front of them. That’s backwards.
The funny part? Most property headaches don’t suddenly appear on settlement day. They creep in weeks before. A contract clause gets skimmed over. A title search raises a question; nobody follows up. Someone assumes another person has already checked something. Then everybody starts scrambling because deadlines don’t wait.
That’s why conveyancing in Essendon has become part of the conversation much earlier than it used to be. Buyers aren’t only searching for someone to finish paperwork anymore. They’re trying to avoid getting caught out after they’ve already fallen in love with a property. Makes sense.
The House Isn’t Always the Risk
We’ve noticed people spend hours looking at kitchens. Fair enough. They inspect bathrooms, fences, gardens and garage doors, yet the paperwork often gets five rushed minutes before a signature goes on the page. That’s where things usually go sideways.
Property contracts carry more than a purchase price. They include conditions, timelines, disclosures, title information and legal obligations that don’t disappear simply because everyone wants a quick settlement.
We’ve seen buyers become completely focused on winning the property while forgetting that buying the wrong contract can cost far more than missing out on the house itself.
That’s one reason conveyancing in Essendon has become something buyers organise before making an offer instead of after.
The earlier someone starts reading through documents properly, the more room there is to ask questions without pressure building. Simple.
Fast Doesn’t Always Mean Smooth
People love quick deals. Nobody enjoys messy ones. Rebecca Lawson, a senior property transactions consultant, put it neatly:
“The smoothest settlements usually aren’t the fastest—they’re the ones where contract reviews, property searches, and communication start well before deadlines become urgent.”
That line sticks with us because it matches what happens in real property transactions. A settlement that finishes on time usually isn’t the result of luck.
It’s the result of dozens of ordinary jobs getting done early. Contract reviews. Section 32 checks. Property searches. Communication with lenders. Small jobs, really. But together they stop much bigger problems from showing up later.
That’s exactly why conveyancing in Essendon isn’t simply about settlement day. Most of the real work happens long before anyone picks up the keys.
Communication Beats Cheap Quotes
Everybody compares prices. Almost everybody. What buyers often remember later isn’t saving a couple of hundred dollars. It’s whether somebody actually answered the phone when things became confusing.
Industry estimates suggest nearly 73% of first-home buyers place regular updates and clear communication above finding the lowest fee. Honestly? We’re not surprised.
Buying property already comes with enough unknowns. Loan approval. Building inspections. Moving dates. Insurance. Utility connections. There’s already plenty happening without wondering whether your conveyancer has disappeared for a week.
We’ve watched people become anxious simply because nobody explained what was happening next. A quick phone call fixes that. An email saying, “Here’s where things stand,” fixes that too.
That’s why people searching for conveyancing in Essendon increasingly ask about communication before they ask about price. Funny how priorities change once real money is involved.
Property Has Gone Digital, But People Still Matter
Paper files are disappearing. People aren’t. Around 82% of Victorian property settlements now happen through PEXA, the electronic settlement platform that’s become standard across much of Australia. Most buyers never log into it. They don’t have to.
What they notice is that documents move electronically, settlement happens online and much of the paperwork that once travelled between offices now moves digitally instead.
Behind all that sits ARNECC and its Model Participation Rules, which set the rules around electronic conveyancing, identity checks and how practitioners complete digital settlements.
Sounds technical. It is. But software doesn’t answer nervous buyers asking whether settlement is still on track. People do. Technology speeds things up. Experience still makes the difference.
That’s another reason conveyancing in Essendon isn’t becoming less personal simply because more work happens online.
Local Knowledge Still Solves Local Problems
Everything feels digital now. Even so, local knowledge still counts. Council requirements differ. Planning overlays differ. Title issues aren’t always identical from one suburb to the next. We’ve seen buyers assume property law works exactly the same everywhere. Not always.
Someone familiar with Essendon property transactions may already know the kinds of questions worth asking before deadlines arrive.
That doesn’t mean online services are bad. Not at all. It simply means local experience can sometimes spot things a broader, centralised process may not notice straight away.
Local Office or Large Online Service?
Both have their place. The better choice depends on how you like working.
| Aspect | Local Conveyancing Service in Essendon | Large Online Conveyancing Service |
| Local property knowledge | Familiar with Essendon council processes, Victorian property requirements and common local title issues | May work through centralised teams with broader but less location-specific knowledge |
| Client communication | Direct contact through local meetings, phone calls or email with the same conveyancer handling the matter | Often managed through online portals, shared inboxes or rotating support staff |
| Settlement support | Personal guidance from contract review through settlement and after settlement questions | Standard workflows designed for high transaction volumes |
The comparison isn’t really about picking a winner. Some buyers like sitting across a desk. Others are happy handling everything online. Different people. Different preferences.
The Smartest Move Usually Happens First
Industry estimates suggest around 88% of Victorian buyers work with a conveyancer or property lawyer before settlement. That figure says plenty. People know the paperwork matters. What’s changing is when they begin.
Instead of waiting until contracts have already been signed, more buyers are organising conveyancing in Essendon before making offers, before cooling-off periods begin and before deadlines pile up.
We’ve noticed that the calmest settlements rarely happen because everything was perfect. They happen because somebody asked the right question at the right time.
That’s probably the biggest lesson here. Conveyancing in Essendon from Easy Link Conveyancing isn’t really about forms or signatures. It’s about catching problems while they’re still easy to fix, keeping communication moving and making sure settlement day feels ordinary instead of stressful. By the time the keys change hands, most of the hard work should already be finished. That’s exactly what good conveyancing in Essendon is supposed to do.
-
 NEWS1 year ago
Historical Churches in Manila
-
 TOPIC2 months ago
Unveiling AvTub: Your Ultimate Guide to the Best AV Content
-
 TOPIC1 year ago
Symbols of Hope: The 15th Belenismo sa Tarlac
-
 TOPIC1 year ago
RIZAL at 160: a Filipino Feat in Britain
-
 TOPIC1 year ago
“The Journey Beyond Fashion” – Ditta Sandico
-
 TOPIC1 month ago
Understanding Fascisterne: Origins and Ideological Roots
-
 TOPIC1 year ago
Simbang Gabi and Kakanin
-
 TOPIC1 year ago
5 Must-Have Products From Adarna House to Nurture Your Roots