HEALTH
Understanding Your Options for a Straighter Smile

Do you feel self conscious about crooked or crowded teeth? There are many options, such as braces, clear aligners, or cosmetic fixes. This post will explain each choice, the time and cost, and who they help.
Keep reading.
Traditional Orthodontic Options
Traditional orthodontic options offer a variety of methods for straightening teeth. They include choices like metal braces and ceramic braces, which can help fix alignment issues effectively.
Metal Braces
Metal braces are common in orthodontics. They use metal brackets and wires to move teeth into better alignment. This option treats moderate to severe malocclusion and crowded teeth.
Typical treatment lasts 12 to 24 months depending on the case.
Metal braces cost less than many clear aligners and aligner systems. Insurance often covers part of the cost for orthodontic care. Patients need regular oral care and careful brushing to protect enamel.
Adjustments occur every 4 to 8 weeks to keep progress on track.
Ceramic Braces
After metal braces, ceramic braces offer a less visible choice. They use tooth-colored brackets and clear wires. Patients prefer them for a more natural look. They still move teeth with steady pressure to improve alignment.
Ceramic braces cost more than metal for some cases. The brackets can chip more easily than steel ones. Stains can occur from dark foods and drinks without careful cleaning. Good oral care and regular dental visits help protect enamel and gum health.
Orthodontists may pick ceramic braces for mild to moderate malocclusion and cosmetic dentistry goals.
Lingual Braces
Moving from ceramic braces, lingual braces attach to the back of the teeth so they stay out of sight. They work like metal braces, using brackets and wires to move teeth into better alignment.
Many adults pick lingual braces for cosmetic dentistry reasons and smile makeovers. Dentists note they can affect speech at first and may cost more than other options. Orthodontists recommend them for complex alignment issues that clear aligners cannot fix.
Modern Clear Aligner Systems
Modern clear aligners offer a discreet way to straighten teeth. Brands like Invisalign® work by gently moving teeth into the right position without metal brackets.
Invisalign® and Similar Brands
Invisalign® is a popular brand of clear aligners. These aligners can fix teeth alignment issues without metal braces. They are made from a smooth plastic that fits snugly over your teeth.
Patients usually wear each set for about two weeks before moving to the next one. This process continues until the treatment is complete.
Similar brands also offer clear aligner options. Each brand provides different features and benefits, but they all aim to straighten teeth discreetly. Clear aligners are easier to remove than traditional braces, making eating and cleaning simple.
Many people appreciate this flexibility as it helps them maintain good oral health throughout their treatment.
Cosmetic Teeth Straightening Options
Cosmetic teeth straightening offers ways to improve your smile. You can use methods like veneers or dental bonding for quick fixes and a better look.
Porcelain Veneers
Porcelain veneers change the look of teeth. They are thin shells made from ceramic material. Dentists bond these shells to the front of your teeth. This process corrects color, shape, or size issues.
Veneers can also fix minor alignment problems.
This option creates a bright and even smile quickly. Many people choose porcelain veneers for a smile makeover. The result looks natural and enhances smile aesthetics. Care for them like regular teeth; proper oral care helps maintain their shine and strength.
Dental Bonding
Moving on from porcelain veneers, dental bonding is another way to improve your smile. This method uses a tooth-colored resin to correct flaws in teeth. It can fill gaps, cover stains, or fix chips and cracks.
The process is quick and often done in one visit. A dentist applies the resin directly to the tooth and shapes it carefully. After that, they use a special light to harden the material.
Dental bonding can enhance your teeth alignment without needing braces or clear aligners. It’s a cost-effective solution for those looking for cosmetic dentistry options too.
Alternative Solutions for Minor Adjustments
Dental retainers can help keep your teeth in place after braces. Reshaping techniques can fix small issues with tooth alignment quickly and easily.
Dental Retainers
Dental retainers keep teeth in place after braces or clear aligners. They help maintain your new smile by preventing teeth from shifting back into their old positions. Retainers come in different types, including removable and fixed options.
Removable retainers are easy to clean and can be taken out when eating or brushing. Fixed retainers are bonded to the back of your teeth for constant support. Each type has its benefits, so it is important to discuss which option suits you best with your orthodontist.
Regularly wearing a retainer will help ensure that your smile stays straight over time.
Reshaping Techniques
Dental retainers can help keep teeth in place after braces or clear aligners. For some, reshaping techniques may be a faster option for minor adjustments. These methods include dental bonding and enamel contouring.
Dental bonding uses tooth-colored material to fix uneven edges or small gaps. This process is quick and often completed in one visit. Enamel contouring involves gently reshaping the outer layer of the tooth to create a better appearance.
Both techniques enhance smile aesthetics without major orthodontic work. They are great choices for those seeking a straighter smile quickly and easily.
Factors to Consider When Choosing an Option
When choosing a teeth straightening option, think about your budget and how long the treatment will take. Also, consider how severe your alignment problems are. Patients in New York searching for Invisalign in Queens NY benefit from consulting an experienced local orthodontist who can assess whether clear aligners are the right fit for their specific case, since not all alignment issues qualify for aligner treatment alone.
Budget and Treatment Duration
Consider cost and time before choosing treatment.
| Option | Typical Cost (USD) | Treatment Duration | Summary Points |
|---|---|---|---|
| Metal Braces | $3,000 to $7,000 | 18 to 36 months |
– Most affordable for complex cases.
– Works well for children and adults. – Insurance may cover part of cost. |
| Ceramic Braces | $4,000 to $8,000 | 18 to 36 months |
– Less visible than metal brackets.
– Higher cost and more fragile parts. – Staining can occur with some foods. |
| Lingual Braces | $8,000 to $13,000 | 18 to 36 months |
– Hidden behind teeth for discreet wear.
– May cause initial speech changes. – Specialist fees often increase total cost. |
| Clear Aligners (Invisalign and similar) | $3,000 to $8,000 | 6 to 18 months |
– Removable trays aid oral hygiene.
– Best for mild to moderate misalignment. – Success depends on patient compliance. |
| Porcelain Veneers | $800 to $2,500 per tooth | 2 to 6 weeks |
– Instant cosmetic straightening.
– Requires some enamel removal. – Not a true orthodontic fix for bite issues. |
| Dental Bonding | $300 to $600 per tooth | 1 to 2 visits |
– Quick and cost effective for small gaps.
– Material may stain over time. – Often reversible in the short term. |
| Dental Retainers | $100 to $500 | Months to lifetime |
– Keeps teeth in place after treatment.
– Some cases use retainers for minor changes. – Replacement costs add up over years. |
| Reshaping Techniques (Enameloplasty) | $50 to $300 per tooth | Single visit |
– Smooths small uneven edges fast.
– Best for minor cosmetic tweaks. – Dentist evaluates tooth structure first. |
| Other Considerations | N/A | Varies |
– Location and provider affect final price.
– Some plans offer in-office financing. – Complex bites need longer care and higher fees. |
Severity of Alignment Issues
Severity guides treatment choice.
| Severity Level | Typical Issues | Recommended Options | Typical Treatment Time | Approximate Cost | Notes |
|---|---|---|---|---|---|
| Mild | Mild cases include gaps under 3 mm. | Clear aligners work well. | Typical time spans are 3 to 6 months. | Costs range $1,500 to $5,000. | Veneers may mask small misalignment. |
| Moderate | Moderate cases include crowding 3 to 6 mm. | Braces or aligners correct these. | Treatment usually lasts 6 to 18 months. | Price often falls between $3,000 and $8,000. | Tooth extraction might be recommended in some cases. |
| Severe | Severe cases show major crowding or large bite issues. | Orthognathic surgery may be needed. | Expect 18 to 36 months or more. | Costs can exceed $6,000 to $12,000. | Specialist referral often improves outcomes. |
| Functional Concerns | Functional problems include chewing and speech impacts. | Combined orthodontic and restorative care helps. | Timelines vary by procedure and age. | Estimates depend on treatment mix and insurance. | Early treatment helps children. |
| Retention | Relapse risk rises without maintenance. | Retainers preserve results long term. | Many patients wear retainers nightly for years. | Retainer costs range from $150 to $500. | Regular follow up reduces future correction need. |
Conclusion
A straighter smile can boost your confidence. Many options exist to achieve this. You may choose traditional braces, clear aligners, or cosmetic fixes like veneers. Each choice fits different needs and budgets.
Take time to explore these paths for a healthy and beautiful smile.
Feeling constantly drained is a common problem in modern life. Many people try to refresh with screen time or passive lounging. Standard relaxation methods often leave you feeling more exhausted than before. True recovery requires deliberate recreational choices. You need daily routines that return real power to your body and mind.
Pinpoint Your Personal Energy Drains
Every person experiences fatigue differently throughout the week. Mental burnout demands a different recovery plan than physical tiredness. The key is to identify where you use the most energy and focus on finding what restores you in those particular areas. Taking time to check your habits helps you spot burnout triggers early.
Finding local spots for relaxation can transform a stressful week into a balanced routine. If you want to unwind after work, stopping by a Nola Cannabis Dispensary provides great options for evening downtime. Taking time to choose products tailored to your needs helps you create a reliable night habit.
Embrace the Power of Micro-Rest
Taking a full weekend off is not always possible with a busy schedule. Short breaks scattered through the day offer a clear alternative. Micro-rest isn’t laziness – it’s efficiency. Pausing for five minutes between tasks gives your brain a chance to reset.
Brief physical shifts help reset your focus during a busy workday:
- Stand up and stretch every hour to improve blood flow.
- Step away from screens during short lunch breaks to rest your eyes.
- Practice slow deep breathing to release physical stress quickly.
These short pauses also give your mind a clean slate. It helps you build mental stamina for tough tasks without taking up much time. You can return to a task with fresh eyes and a calmer mood. Small rests add up over a full day and leave you with more energy by evening.
Prioritize Deep Physical Recovery
Sleep quality plays a big role in how you handle daily stress. Around one in three adults don’t get enough rest or sleep. Setting a consistent bedtime routine helps signal to your body that it is time to slow down. Unplugging devices an hour before bed creates the right setting for deep sleep.
Consistent sleep habits boost long-term strength and emotional balance. Creating a dark, cool sleeping space helps you stay asleep longer. Avoiding heavy meals late in the evening prevents night wakeups. Quality sleep forms the base of physical energy.
Engage in Unplugged Hobbies
Passive habits like watching short videos rarely restore mental sharpness. Active time spent on a simple hobby works much better. Gardening, cooking, or playing music forces your mind into a relaxed state. Simple hobbies pull your focus away from work stress and rebuild your focus.
Hands-on hobbies give your brain a break from daily problem-solving. Working on a creative project without tight deadlines offers complete personal freedom. You build fresh mental paths as you step away from digital noise. Engaging your senses outdoors adds to these restorative benefits.
Reclaim Your Daily Balance
Building effective rest routines takes simple trial and error. Listen to physical cues and adjust habits as needed. Start integrating small recovery moments into your schedule today to rebuild your energy and well-being.
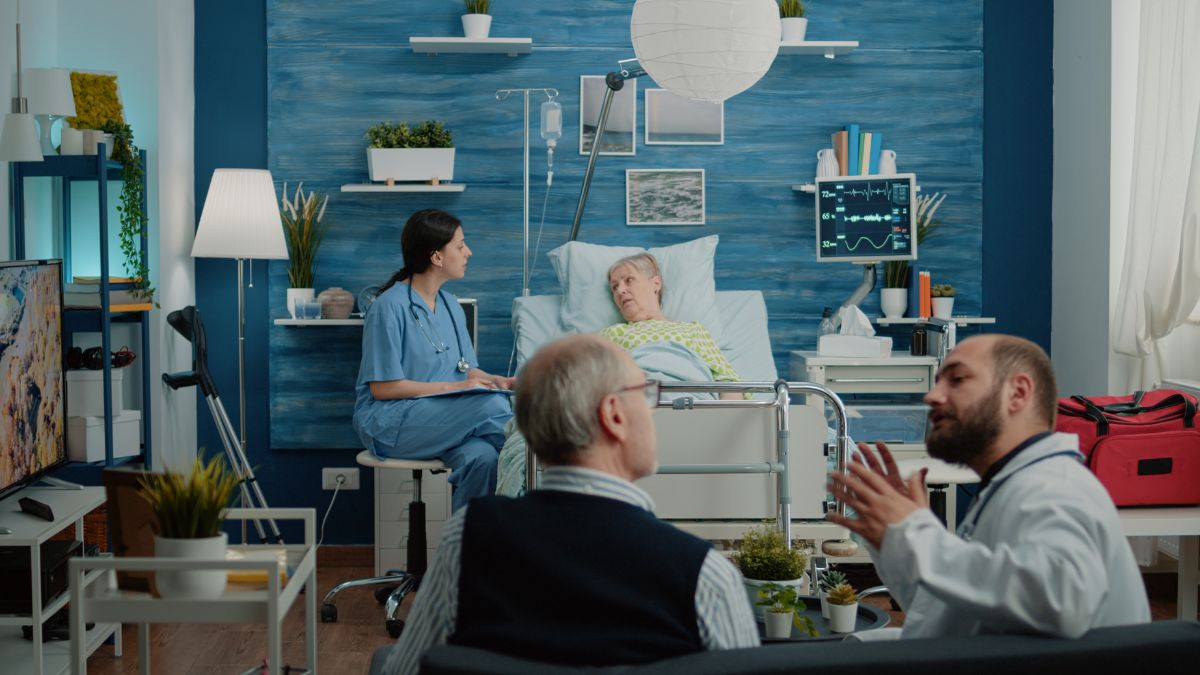
Choosing hospice care is a deeply personal decision, and families often have to make it while also managing uncertainty, stress, and changing care needs. In Taos, NM, quality hospice care should provide more than basic medical support. A strong hospice team should communicate clearly, respect the wishes of the patient and family, coordinate care carefully, and help create as much comfort and stability as possible during a difficult stage of life.
Compassion Is Reflected in Everyday Care
Compassionate hospice care is not only about being kind during major conversations. It should also be visible in the smaller moments, including how team members speak with patients, how carefully they listen, and whether they make time to understand what matters to the individual receiving care.
Patients should be treated with dignity, patience, and respect, regardless of how much their condition has changed. Families should also feel that their questions and concerns are taken seriously rather than brushed aside because the care team is busy.
Does the Hospice Team Communicate Clearly?
Good communication is one of the strongest signs of quality hospice care. Families should understand who is involved in the patient’s care, what each team member does, and whom they should contact when questions or concerns arise.
Hospice professionals should also explain changes in the patient’s condition in straightforward language. Families may already be overwhelmed, so complicated medical terminology without explanation can create unnecessary confusion. A good team takes the time to make information understandable while remaining sensitive to what the family is experiencing.
Care Should Be Built Around the Individual
No two hospice patients have exactly the same needs, priorities, or preferences. A quality hospice provider should develop care around the individual rather than forcing every patient into the same routine.
Some patients may place the greatest importance on controlling pain or other uncomfortable symptoms, while others may focus more heavily on remaining at home, maintaining familiar routines, or spending meaningful time with family. A thoughtful care plan should reflect those priorities and adjust when the patient’s needs change.
Families Receive Support, Too
Hospice care centers on the patient, but families and caregivers are also an important part of the process. Loved ones may be helping with everyday care while simultaneously trying to understand physical changes, medication schedules, equipment, and what to expect next.
A good hospice team helps caregivers feel more prepared. That can include answering practical questions, explaining how to respond to common changes, and helping families understand when they should contact the hospice team for additional guidance.
Is Symptom Management Taken Seriously?
Comfort is one of the central goals of hospice care, which makes careful symptom management especially important. Pain is often the first concern people think about, although patients may also experience shortness of breath, nausea, restlessness, fatigue, anxiety, or other uncomfortable symptoms.
Quality hospice professionals should regularly assess how the patient is feeling and respond when symptoms change. Good symptom management is not a one-time task completed at the beginning of care. It requires continued observation and adjustments based on the patient’s condition and response to treatment.
The Care Team Works Together
Hospice care is typically provided by a team rather than a single person, which makes coordination essential. Nurses, physicians, aides, social workers, chaplains or spiritual-care professionals, and other team members may contribute different types of support depending on the patient’s needs.
Families should not feel responsible for making separate parts of the care plan fit together on their own. A well-organized hospice team communicates internally, shares relevant information, and works toward consistent goals for the patient.
Respect for Personal and Cultural Preferences Matters
Taos is a community with distinctive cultural traditions, family structures, and spiritual perspectives, and hospice care should leave room for those differences. Patients and families may have specific wishes involving visitors, ceremonies, spiritual practices, food, communication, or the people they want involved in important decisions.
Quality care does not assume that every family wants the same experience. Instead, hospice professionals should ask respectful questions, listen carefully, and incorporate reasonable personal preferences into the care plan whenever possible.
Reliable Availability Builds Confidence
Changes can occur outside normal business hours, which is why families should understand how to reach hospice support when they need guidance. Knowing that there is a clear process for getting help can reduce uncertainty, particularly when caregivers encounter a symptom or situation they have not seen before.
Reliability also includes following through on promised communication, coordinating needed supplies or equipment, and keeping families informed when plans change. Consistency often matters just as much as friendliness because families need to know they can depend on the people involved in their loved one’s care.
Quality Care Includes Emotional Support
Hospice involves physical care, although the emotional side of the experience can be equally significant. Patients may experience fear, frustration, sadness, or uncertainty, while family members may be dealing with anticipatory grief and difficult decisions.
A supportive hospice team recognizes that these feelings are part of the experience rather than treating them as distractions from medical care. Emotional, social, and spiritual support can help patients and families feel less isolated while they navigate unfamiliar circumstances.
Recognizing Quality Hospice Care in Taos
Quality hospice care in Taos, NM, should feel personal, organized, respectful, and responsive. Strong communication, careful symptom management, coordinated teamwork, caregiver support, and respect for the patient’s preferences are all important signs that a hospice provider is taking a thoughtful approach to care.
Families should feel comfortable asking questions and learning how a hospice team approaches communication, after-hours needs, symptom changes, and family involvement before making a decision. Taking time to evaluate those qualities can help families choose hospice care that supports comfort, dignity, and meaningful connection throughout the time ahead.
Retirement healthcare planning can be especially important for women because longer life expectancy, caregiving responsibilities, career interruptions, and differences in retirement income can affect how long healthcare costs need to be funded. Planning for Medicare premiums, out-of-pocket expenses, prescriptions, and potential long-term care can help create a more realistic retirement healthcare budget.
Key Takeaways
- Women may need to budget for healthcare expenses over a longer retirement because they generally live longer than men.
- Medicare does not cover every healthcare expense, so premiums, prescriptions, dental and vision care, and other out-of-pocket costs should be included in retirement planning.
- Caregiving and career interruptions can affect both current income and long-term retirement savings.
- Long-term care deserves separate consideration because Medicare generally does not cover most ongoing long-term care services.
Retirement healthcare challenges for women can look different from those men face. A longer average lifespan, caregiving responsibilities, career interruptions, and differences in retirement income can all affect how women prepare for healthcare expenses after leaving the workforce.
That does not mean women will automatically spend more on every type of healthcare. It means the number of years they may need coverage, the type of care they may need, and the resources available to pay for it can differ.
For women approaching retirement, looking beyond the monthly insurance premium can make the difference between a manageable healthcare budget and one that gets stretched quickly.
In this blog, we explore the key retirement healthcare challenges for women and how they can prepare for future healthcare costs.
| Quick Answer: Women preparing for retirement should estimate healthcare costs beyond insurance premiums, account for potentially longer retirement years, consider caregiving and income interruptions, review Medicare coverage carefully, and create a separate plan for potential long-term care. |
1. Women Typically Need to Plan for More Years of Healthcare Costs
One of the biggest differences is longevity. Women generally live longer than men, which can mean more years of healthcare expenses after leaving the workforce.
That longer lifespan can extend the period during which a woman needs to pay for Medicare premiums, prescription medications, doctor visits, dental care, vision services, and other out-of-pocket expenses. Even modest annual costs can add up when they continue for several additional years.
For that reason, women’s retirement healthcare planning needs to account for the possibility of a longer retirement rather than stopping at a specific age.
| What This Means For You: Planning only through age 75 or 80 may leave a gap if you live well into your 80s or 90s. A retirement healthcare budget should account for the possibility of many years of premiums and out-of-pocket healthcare expenses. |
How Longevity Changes Retirement Planning
Fidelity estimates that a 65-year-old retiring in 2026 may spend $185,500 on healthcare throughout retirement. With costs like these, an extra five or ten years of healthcare expenses can significantly affect retirement savings. A woman retiring at 65 may need to budget for healthcare into her 80s or 90s.
That makes retirement healthcare planning part of the broader retirement conversation rather than a decision made after leaving work.
2. Women May Spend More Years Managing Chronic Health Conditions
Age can bring more frequent healthcare needs for anyone. Regular prescriptions, specialist visits, testing, and ongoing treatment can all become recurring expenses.
For women, that may mean healthcare needs continue for many years after retirement. The cost is also about more than the insurance premium. A plan with a low monthly premium may still result in higher annual spending if it comes with substantial deductibles, copayments, or prescription costs.
This is why healthcare costs in retirement must be estimated based on expected use of care, not just the price of coverage.
Recurring Healthcare Costs Add Up
A retirement healthcare budget may need to include:
- Monthly Medicare premiums
- Deductibles and coinsurance
- Prescription medications
- Specialist visits
- Dental and vision care
- Medical equipment or supplies
- Services not covered by Medicare
The right estimate will vary from person to person, but overlooking smaller recurring expenses can leave a noticeable gap in a retirement budget.
3. The Caregiving Burden Can Affect Women’s Retirement Security
Women may also need to balance their own healthcare with caregiving for a parent, spouse, or other family member. In 2026, the Administration for Community Living reported that more than 70 million people provide paid or unpaid caregiving.
Taking time off work or covering care-related expenses can reduce income and retirement savings, making caregiving a factor worth including in women’s retirement healthcare planning.
| Research Says: The Administration for Community Living says more than 70 million paid and unpaid caregivers provide support that helps older adults and people with disabilities live independently. Its 2025 caregiver fact sheet also reports that 63 million Americans, about 1 in 4 adults, provide ongoing care for older adults and people with disabilities. |
4. Time Away From Work Can Affect Health Insurance and Retirement Savings
Career interruptions may contribute to differences in retirement income. In December 2025, women represented a larger share of retired-worker beneficiaries, with 27.6 million women compared with 26.0 million men, but their average monthly benefit was $409.85 lower. This difference should be considered when estimating how women will cover healthcare costs, including premiums, deductibles, prescriptions, and other expenses, particularly if they retire before becoming eligible for Medicare.
5. Medicare Might Not Cover Every Retirement Healthcare Expense
Medicare can cover a substantial share of eligible medical services, but it does not mean healthcare becomes free at 65.
For 2026, the standard Medicare Part B premium is $202.90 per month, while the annual Part B deductible is $283. Higher-income beneficiaries can pay additional income-related charges.
Medicare also does not cover every service or expense a person may need throughout retirement. Routine dental, vision, hearing services, prescription drug costs, and certain long-term care needs can require additional planning or coverage.
| Common Mistake: Assuming that becoming eligible for Medicare means most retirement healthcare expenses will be covered can lead to an unrealistic retirement budget. Medicare still involves premiums and cost-sharing, and some services require separate coverage or out-of-pocket payment. |
What to Review Before Retirement
Before enrolling in Medicare, review:
- Medicare eligibility and enrollment timing
- Prescription drug coverage
- Supplemental coverage options
- Expected medical expenses
- Dental and vision needs
- Potential long-term care expenses
6. Long-Term Care Deserves a Separate Place in the Plan
Long-term care goes beyond routine medical treatment and may include help with daily activities, assisted living, nursing care, or support at home.
The Administration for Community Living reports that someone turning 65 today has nearly a 70% chance of needing long-term care at some point. For women who may spend more years in retirement, long-term care planning can help account for these potential costs.
It is worth considering how extended care could affect retirement savings, family finances, and independence.
7. How Women Can Prepare for Retirement Healthcare Costs
A good retirement healthcare planning strategy starts well before retirement. A few practical steps can make future expenses easier to estimate.
- Estimate healthcare expenses beyond premiums: Include deductibles, prescriptions, copayments, dental care, vision care, and other recurring costs.
- Review Medicare and supplemental coverage: Compare coverage based on the care you expect to use rather than choosing solely by premium.
- Account for prescription costs: Regular medications can become a significant part of annual healthcare spending, particularly when several prescriptions are involved.
- Build a long-term care strategy: Consider how you would pay for extended care at home, in an assisted living facility, or in a nursing facility.
- Revisit the plan as your needs change: Retirement healthcare is not a one-time decision. Changes in health, income, coverage, and family responsibilities can all affect the amount you need to set aside.
Plan for the Retirement Healthcare You May Actually Need
Women may face more years of healthcare spending in retirement, along with financial pressures from caregiving and career interruptions. That makes healthcare expenses in retirement worth considering alongside housing, travel, and everyday living costs.
You do not need to predict every medical expense years ahead. Start by reviewing your Medicare options, expected healthcare needs, prescription costs, and potential long-term care expenses.
If you would like help sorting through these choices, Terri Yurek Insurance provides Medicare education and coverage guidance for individuals preparing for retirement. With more than 20 years of experience, Terri Yurek focuses on making Medicare easier to understand through education and personalized guidance. Her agency also offers zero-cost, no-pressure Medicare education courses for people preparing for this stage of retirement.
A conversation with a knowledgeable insurance professional can help you better understand your coverage choices and how they fit into your broader retirement plan.
| Next Step: Before making a Medicare decision, create a simple retirement healthcare estimate that includes premiums, prescriptions, expected medical care, dental and vision expenses, and potential long-term care costs. Then review the estimate against your expected retirement income. |
Frequently Asked Questions (FAQs)
1. Do women typically have higher healthcare costs in retirement?
- They may have higher lifetime healthcare spending, partly because women generally live longer and may spend more years managing ongoing health needs or paying for long-term care.
2. Does Medicare cover all retirement healthcare costs?
- Medicare still leaves premiums, deductibles, coinsurance, and copayments. Routine dental and vision care may also require separate coverage or out-of-pocket spending.
3. How should women prepare for long-term care?
- Consider long-term care separately from routine medical expenses. Estimate potential costs and consider how insurance, savings, and other resources could help cover extended care.
4. When should women start planning for retirement healthcare?
- Ideally, start several years before retirement. This gives you time to review Medicare, estimate future expenses, and adjust your savings or coverage as needed.
-
 NEWS1 year ago
Historical Churches in Manila
-
 TOPIC3 months ago
Unveiling AvTub: Your Ultimate Guide to the Best AV Content
-
 TOPIC1 year ago
Symbols of Hope: The 15th Belenismo sa Tarlac
-
 TOPIC1 year ago
RIZAL at 160: a Filipino Feat in Britain
-
 TOPIC1 year ago
Simbang Gabi and Kakanin
-
 TOPIC2 months ago
Understanding Fascisterne: Origins and Ideological Roots
-
 TOPIC1 year ago
“The Journey Beyond Fashion” – Ditta Sandico
-
 NEWS4 months ago
What Caused Delta Flight DL275 to Diverted LAX? A Detailed Breakdown