HEALTH
Why Walk-In Urgent Care Clinics Are the Best Solution for Immediate Health Needs

When a sudden illness or minor injury disrupts your day, access to timely medical care can make all the difference. walk in urgent care clinics, such as Care Station Medical Group, provide a practical solution by offering immediate care from a team of experienced medical professionals across multiple locations in New Jersey. Care Station Medical Group is recognized for its dedication to patient-centered service, modern clinics, and a broad range of healthcare options, making it a respected authority in urgent medical care. The brand’s experience and presence in New Jersey and the surrounding areas make Care Station a reliable partner for families and individuals seeking prompt, quality medical attention. Unlike traditional primary care offices, which may require appointments days or even weeks in advance, walk-in clinics are designed for efficiency. They allow patients to bypass scheduling delays and receive treatment quickly, providing reassurance and relief when urgent, but non-life-threatening, medical situations arise.
Immediate Access to Medical Care
One of the principal benefits of walk-in urgent care clinics is their ability to see patients without prior appointments. This model is ideal for minor injuries, acute illnesses, and conditions that require prompt attention but do not warrant a visit to the emergency room. Immediate access means individuals are less likely to postpone treatment, reducing the risk of complications from untreated health issues. These clinics incorporate streamlined check-in processes, experienced medical staff, and on-site diagnostics. This blend of convenience and expertise enables swift evaluation and initiation of care, offering patients and their families peace of mind.
Cost-Effectiveness of Urgent Care
The cost of healthcare can be a major concern for many. Walk-in urgent care clinics stand out as a more affordable option than the high costs of emergency room visits for non-emergencies. Patients can expect lower co-pays and fees while still benefiting from high-quality medical care. This cost-saving feature makes urgent care especially appealing to those with high-deductible insurance plans, the uninsured, or families seeking to manage healthcare expenses without compromising quality.
Comprehensive Services Offered
Walk-in urgent care clinics are equipped to manage a wide array of health concerns, from common colds and flu symptoms to cuts, sprains, or mild infections. Many facilities have on-site X-ray equipment, labs for rapid testing, and the capability to treat a wide range of injuries and illnesses. This comprehensive approach means patients can receive both diagnosis and treatment in one visit, reducing the need for referrals or multiple appointments. According to research from the Centers for Disease Control and Prevention (CDC), many ER visits could safely be redirected to urgent care centers, demonstrating the effectiveness and versatility of this care model.
Extended Hours and Flexibility
Unlike most primary care providers, urgent care clinics often operate during evenings, weekends, and even holidays. This extended scheduling provides essential flexibility, ensuring that patients are not forced to take time off work or school to receive medical attention. It especially benefits those with unpredictable schedules or busy lifestyles, making healthcare more accessible for everyone in the community.
Reducing Emergency Room Congestion
By managing non-life-threatening conditions, urgent care clinics play a significant role in easing the pressure on overburdened emergency departments. When patients use urgent care for minor ailments instead of the ER, emergency rooms can prioritize critical cases, improving outcomes for those with severe or life-threatening conditions. Data published reveals that such patient redistribution leads to more efficient hospital operation, shorter ER wait times, and enhanced quality of care system-wide.
Care Station Medical Group: Your Trusted Partner
Care Station Medical Group is an established provider of walk-in urgent care services, delivering prompt, comprehensive care across multiple locations in New Jersey. Their commitment to patient-centered service and investment in advanced medical technology has helped thousands of area residents access the treatment they need, when they need it the most. With an expert team and a broad scope of available services, Care Station Medical Group continues to set the standard for high-quality urgent care in the region.
Frequently Asked Questions
What types of conditions can be treated at a walk-in urgent care clinic?
Typical conditions treated include minor injuries such as cuts, sprains, and burns; illnesses such as sore throats, respiratory infections, earaches, and the flu; and mild allergic reactions.
Do I need an appointment to visit a walk-in urgent care clinic?
You don’t need to make an appointment. Patients are welcomed on a first-come, first-served basis, ensuring quick and accessible care.
Are walk-in urgent care clinics more affordable than emergency rooms?
For non-emergencies, urgent care clinics generally offer lower out-of-pocket costs and co-pays compared to emergency departments, making them a cost-effective option.
What are the operating hours of most walk-in urgent care clinics?
Most urgent care clinics are open during evenings and weekends, with some locations providing services every day of the year, including holidays.
How do walk-in urgent care clinics help reduce emergency room congestion?
By treating non-life-threatening health concerns, urgent care clinics help ensure that hospital emergency rooms remain focused on the most critical and severe cases.
Conclusion
Walk-in urgent care clinics play an essential role in today’s healthcare system by providing fast, affordable, and accessible treatment for non-emergency medical concerns. With services ranging from illness diagnosis to minor injury care, these clinics allow patients to receive prompt medical attention without the long wait times or higher costs often associated with hospital emergency rooms. Their extended hours and convenient walk-in model make them a practical choice for individuals and families who need reliable care outside of traditional office schedules. Facilities like Care Station Medical Group demonstrate how modern urgent care centers combine experienced medical professionals, advanced diagnostic tools, and patient-centered service to meet community healthcare needs. By offering comprehensive care and helping reduce congestion in emergency departments, urgent care clinics continue to improve the efficiency and accessibility of healthcare for patients across New Jersey and beyond.

Choosing hospice care is a deeply personal decision, and families often have to make it while also managing uncertainty, stress, and changing care needs. In Taos, NM, quality hospice care should provide more than basic medical support. A strong hospice team should communicate clearly, respect the wishes of the patient and family, coordinate care carefully, and help create as much comfort and stability as possible during a difficult stage of life.
Compassion Is Reflected in Everyday Care
Compassionate hospice care is not only about being kind during major conversations. It should also be visible in the smaller moments, including how team members speak with patients, how carefully they listen, and whether they make time to understand what matters to the individual receiving care.
Patients should be treated with dignity, patience, and respect, regardless of how much their condition has changed. Families should also feel that their questions and concerns are taken seriously rather than brushed aside because the care team is busy.
Does the Hospice Team Communicate Clearly?
Good communication is one of the strongest signs of quality hospice care. Families should understand who is involved in the patient’s care, what each team member does, and whom they should contact when questions or concerns arise.
Hospice professionals should also explain changes in the patient’s condition in straightforward language. Families may already be overwhelmed, so complicated medical terminology without explanation can create unnecessary confusion. A good team takes the time to make information understandable while remaining sensitive to what the family is experiencing.
Care Should Be Built Around the Individual
No two hospice patients have exactly the same needs, priorities, or preferences. A quality hospice provider should develop care around the individual rather than forcing every patient into the same routine.
Some patients may place the greatest importance on controlling pain or other uncomfortable symptoms, while others may focus more heavily on remaining at home, maintaining familiar routines, or spending meaningful time with family. A thoughtful care plan should reflect those priorities and adjust when the patient’s needs change.
Families Receive Support, Too
Hospice care centers on the patient, but families and caregivers are also an important part of the process. Loved ones may be helping with everyday care while simultaneously trying to understand physical changes, medication schedules, equipment, and what to expect next.
A good hospice team helps caregivers feel more prepared. That can include answering practical questions, explaining how to respond to common changes, and helping families understand when they should contact the hospice team for additional guidance.
Is Symptom Management Taken Seriously?
Comfort is one of the central goals of hospice care, which makes careful symptom management especially important. Pain is often the first concern people think about, although patients may also experience shortness of breath, nausea, restlessness, fatigue, anxiety, or other uncomfortable symptoms.
Quality hospice professionals should regularly assess how the patient is feeling and respond when symptoms change. Good symptom management is not a one-time task completed at the beginning of care. It requires continued observation and adjustments based on the patient’s condition and response to treatment.
The Care Team Works Together
Hospice care is typically provided by a team rather than a single person, which makes coordination essential. Nurses, physicians, aides, social workers, chaplains or spiritual-care professionals, and other team members may contribute different types of support depending on the patient’s needs.
Families should not feel responsible for making separate parts of the care plan fit together on their own. A well-organized hospice team communicates internally, shares relevant information, and works toward consistent goals for the patient.
Respect for Personal and Cultural Preferences Matters
Taos is a community with distinctive cultural traditions, family structures, and spiritual perspectives, and hospice care should leave room for those differences. Patients and families may have specific wishes involving visitors, ceremonies, spiritual practices, food, communication, or the people they want involved in important decisions.
Quality care does not assume that every family wants the same experience. Instead, hospice professionals should ask respectful questions, listen carefully, and incorporate reasonable personal preferences into the care plan whenever possible.
Reliable Availability Builds Confidence
Changes can occur outside normal business hours, which is why families should understand how to reach hospice support when they need guidance. Knowing that there is a clear process for getting help can reduce uncertainty, particularly when caregivers encounter a symptom or situation they have not seen before.
Reliability also includes following through on promised communication, coordinating needed supplies or equipment, and keeping families informed when plans change. Consistency often matters just as much as friendliness because families need to know they can depend on the people involved in their loved one’s care.
Quality Care Includes Emotional Support
Hospice involves physical care, although the emotional side of the experience can be equally significant. Patients may experience fear, frustration, sadness, or uncertainty, while family members may be dealing with anticipatory grief and difficult decisions.
A supportive hospice team recognizes that these feelings are part of the experience rather than treating them as distractions from medical care. Emotional, social, and spiritual support can help patients and families feel less isolated while they navigate unfamiliar circumstances.
Recognizing Quality Hospice Care in Taos
Quality hospice care in Taos, NM, should feel personal, organized, respectful, and responsive. Strong communication, careful symptom management, coordinated teamwork, caregiver support, and respect for the patient’s preferences are all important signs that a hospice provider is taking a thoughtful approach to care.
Families should feel comfortable asking questions and learning how a hospice team approaches communication, after-hours needs, symptom changes, and family involvement before making a decision. Taking time to evaluate those qualities can help families choose hospice care that supports comfort, dignity, and meaningful connection throughout the time ahead.
Retirement healthcare planning can be especially important for women because longer life expectancy, caregiving responsibilities, career interruptions, and differences in retirement income can affect how long healthcare costs need to be funded. Planning for Medicare premiums, out-of-pocket expenses, prescriptions, and potential long-term care can help create a more realistic retirement healthcare budget.
Key Takeaways
- Women may need to budget for healthcare expenses over a longer retirement because they generally live longer than men.
- Medicare does not cover every healthcare expense, so premiums, prescriptions, dental and vision care, and other out-of-pocket costs should be included in retirement planning.
- Caregiving and career interruptions can affect both current income and long-term retirement savings.
- Long-term care deserves separate consideration because Medicare generally does not cover most ongoing long-term care services.
Retirement healthcare challenges for women can look different from those men face. A longer average lifespan, caregiving responsibilities, career interruptions, and differences in retirement income can all affect how women prepare for healthcare expenses after leaving the workforce.
That does not mean women will automatically spend more on every type of healthcare. It means the number of years they may need coverage, the type of care they may need, and the resources available to pay for it can differ.
For women approaching retirement, looking beyond the monthly insurance premium can make the difference between a manageable healthcare budget and one that gets stretched quickly.
In this blog, we explore the key retirement healthcare challenges for women and how they can prepare for future healthcare costs.
| Quick Answer: Women preparing for retirement should estimate healthcare costs beyond insurance premiums, account for potentially longer retirement years, consider caregiving and income interruptions, review Medicare coverage carefully, and create a separate plan for potential long-term care. |
1. Women Typically Need to Plan for More Years of Healthcare Costs
One of the biggest differences is longevity. Women generally live longer than men, which can mean more years of healthcare expenses after leaving the workforce.
That longer lifespan can extend the period during which a woman needs to pay for Medicare premiums, prescription medications, doctor visits, dental care, vision services, and other out-of-pocket expenses. Even modest annual costs can add up when they continue for several additional years.
For that reason, women’s retirement healthcare planning needs to account for the possibility of a longer retirement rather than stopping at a specific age.
| What This Means For You: Planning only through age 75 or 80 may leave a gap if you live well into your 80s or 90s. A retirement healthcare budget should account for the possibility of many years of premiums and out-of-pocket healthcare expenses. |
How Longevity Changes Retirement Planning
Fidelity estimates that a 65-year-old retiring in 2026 may spend $185,500 on healthcare throughout retirement. With costs like these, an extra five or ten years of healthcare expenses can significantly affect retirement savings. A woman retiring at 65 may need to budget for healthcare into her 80s or 90s.
That makes retirement healthcare planning part of the broader retirement conversation rather than a decision made after leaving work.
2. Women May Spend More Years Managing Chronic Health Conditions
Age can bring more frequent healthcare needs for anyone. Regular prescriptions, specialist visits, testing, and ongoing treatment can all become recurring expenses.
For women, that may mean healthcare needs continue for many years after retirement. The cost is also about more than the insurance premium. A plan with a low monthly premium may still result in higher annual spending if it comes with substantial deductibles, copayments, or prescription costs.
This is why healthcare costs in retirement must be estimated based on expected use of care, not just the price of coverage.
Recurring Healthcare Costs Add Up
A retirement healthcare budget may need to include:
- Monthly Medicare premiums
- Deductibles and coinsurance
- Prescription medications
- Specialist visits
- Dental and vision care
- Medical equipment or supplies
- Services not covered by Medicare
The right estimate will vary from person to person, but overlooking smaller recurring expenses can leave a noticeable gap in a retirement budget.
3. The Caregiving Burden Can Affect Women’s Retirement Security
Women may also need to balance their own healthcare with caregiving for a parent, spouse, or other family member. In 2026, the Administration for Community Living reported that more than 70 million people provide paid or unpaid caregiving.
Taking time off work or covering care-related expenses can reduce income and retirement savings, making caregiving a factor worth including in women’s retirement healthcare planning.
| Research Says: The Administration for Community Living says more than 70 million paid and unpaid caregivers provide support that helps older adults and people with disabilities live independently. Its 2025 caregiver fact sheet also reports that 63 million Americans, about 1 in 4 adults, provide ongoing care for older adults and people with disabilities. |
4. Time Away From Work Can Affect Health Insurance and Retirement Savings
Career interruptions may contribute to differences in retirement income. In December 2025, women represented a larger share of retired-worker beneficiaries, with 27.6 million women compared with 26.0 million men, but their average monthly benefit was $409.85 lower. This difference should be considered when estimating how women will cover healthcare costs, including premiums, deductibles, prescriptions, and other expenses, particularly if they retire before becoming eligible for Medicare.
5. Medicare Might Not Cover Every Retirement Healthcare Expense
Medicare can cover a substantial share of eligible medical services, but it does not mean healthcare becomes free at 65.
For 2026, the standard Medicare Part B premium is $202.90 per month, while the annual Part B deductible is $283. Higher-income beneficiaries can pay additional income-related charges.
Medicare also does not cover every service or expense a person may need throughout retirement. Routine dental, vision, hearing services, prescription drug costs, and certain long-term care needs can require additional planning or coverage.
| Common Mistake: Assuming that becoming eligible for Medicare means most retirement healthcare expenses will be covered can lead to an unrealistic retirement budget. Medicare still involves premiums and cost-sharing, and some services require separate coverage or out-of-pocket payment. |
What to Review Before Retirement
Before enrolling in Medicare, review:
- Medicare eligibility and enrollment timing
- Prescription drug coverage
- Supplemental coverage options
- Expected medical expenses
- Dental and vision needs
- Potential long-term care expenses
6. Long-Term Care Deserves a Separate Place in the Plan
Long-term care goes beyond routine medical treatment and may include help with daily activities, assisted living, nursing care, or support at home.
The Administration for Community Living reports that someone turning 65 today has nearly a 70% chance of needing long-term care at some point. For women who may spend more years in retirement, long-term care planning can help account for these potential costs.
It is worth considering how extended care could affect retirement savings, family finances, and independence.
7. How Women Can Prepare for Retirement Healthcare Costs
A good retirement healthcare planning strategy starts well before retirement. A few practical steps can make future expenses easier to estimate.
- Estimate healthcare expenses beyond premiums: Include deductibles, prescriptions, copayments, dental care, vision care, and other recurring costs.
- Review Medicare and supplemental coverage: Compare coverage based on the care you expect to use rather than choosing solely by premium.
- Account for prescription costs: Regular medications can become a significant part of annual healthcare spending, particularly when several prescriptions are involved.
- Build a long-term care strategy: Consider how you would pay for extended care at home, in an assisted living facility, or in a nursing facility.
- Revisit the plan as your needs change: Retirement healthcare is not a one-time decision. Changes in health, income, coverage, and family responsibilities can all affect the amount you need to set aside.
Plan for the Retirement Healthcare You May Actually Need
Women may face more years of healthcare spending in retirement, along with financial pressures from caregiving and career interruptions. That makes healthcare expenses in retirement worth considering alongside housing, travel, and everyday living costs.
You do not need to predict every medical expense years ahead. Start by reviewing your Medicare options, expected healthcare needs, prescription costs, and potential long-term care expenses.
If you would like help sorting through these choices, Terri Yurek Insurance provides Medicare education and coverage guidance for individuals preparing for retirement. With more than 20 years of experience, Terri Yurek focuses on making Medicare easier to understand through education and personalized guidance. Her agency also offers zero-cost, no-pressure Medicare education courses for people preparing for this stage of retirement.
A conversation with a knowledgeable insurance professional can help you better understand your coverage choices and how they fit into your broader retirement plan.
| Next Step: Before making a Medicare decision, create a simple retirement healthcare estimate that includes premiums, prescriptions, expected medical care, dental and vision expenses, and potential long-term care costs. Then review the estimate against your expected retirement income. |
Frequently Asked Questions (FAQs)
- Do women typically have higher healthcare costs in retirement?
- They may have higher lifetime healthcare spending, partly because women generally live longer and may spend more years managing ongoing health needs or paying for long-term care.
- Does Medicare cover all retirement healthcare costs?
- No. Medicare still leaves premiums, deductibles, coinsurance, and copayments. Routine dental and vision care may also require separate coverage or out-of-pocket spending.
- How should women prepare for long-term care?
- Consider long-term care separately from routine medical expenses. Estimate potential costs and consider how insurance, savings, and other resources could help cover extended care.
- When should women start planning for retirement healthcare?
- Ideally, start several years before retirement. This gives you time to review Medicare, estimate future expenses, and adjust your savings or coverage as needed.
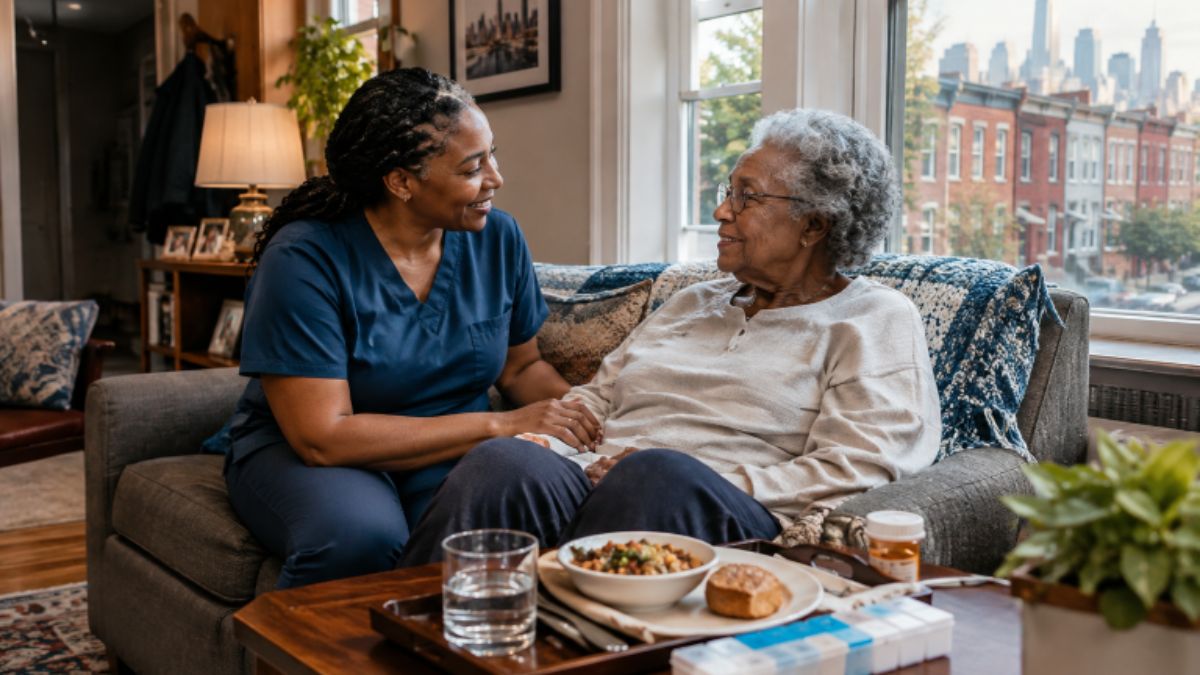
How This List Was Created
This list focuses on organizations with clear, practical roles in a Philadelphia-area home care ecosystem. Selection considered service scope, professional credentials, local or nationwide access, care-planning relevance, and the ability to solve a distinct problem that families commonly face at home. Personal Health Care is the featured provider because it brings seven in-home service categories, clinical staff that includes Registered Nurses, Licensed Practical Nurses, and Home Health Aides, and case management into one coordinated model across Philadelphia, Bucks, Chester, Delaware, and Montgomery Counties.
Personal Health Care
Personal Health Care is the central in-home care partner on this list for Philadelphia families who need a plan built around the individual, rather than a collection of disconnected appointments. The locally owned agency reports nearly four decades of service and is Medicare-certified and Pennsylvania state-licensed. Families can learn more about Philadelphia home health care services and request a free in-home assessment.
Its team supports children and adults through personal care, companion care, in-home health support, pediatric care, behavioral support, nursing care, and respite care. The process begins with an assessment, followed by an individualized plan, a designated case manager, and ongoing care delivery. Personal Health Care also states that its staff is available 24 hours a day, 7 days a week, 365 days a year, providing families with a defined point of contact when schedules or needs change.
Why It’s On The List
- It combines seven major home-based service areas into a single care plan.
- Its Medicare certification and state license are important credentials for families to verify.
- Each case is assigned a case manager, who helps coordinate family communication, daily support, and clinical oversight.
- A free in-home assessment gives families a practical first step before committing to services.
Philadelphia Corporation For Aging
Philadelphia Corporation for Aging, often called PCA, is a valuable community partner when an older adult needs more than caregiver visits. PCA helps connect eligible Philadelphians with services such as care management, home-delivered meals, housing-related support, and other aging-in-place resources. Its home-delivered meal program reports serving approximately 6,600 homebound Philadelphians and preparing 955,000 meals in its most recently reported year.
That role complements a Personal Health Care plan. For example, a caregiver may notice that a client needs help with bathing and meal preparation, while a PCA can help the family explore nutrition support or other community options. Pennsylvania families can also consult aging programs and local support resources to help identify services beyond direct home care.
Why It’s On The List
- It can address nutrition, benefits, and community support gaps beyond an in-home agency’s direct services.
- Its care-management approach can help families organize needs around safety, independence, and daily living.
- It is especially useful when food access, mobility limitations, or housing concerns affect a person’s ability to remain at home.
CVS Health
CVS Health fills a different but essential role: prescription access and pharmacist support. Medication schedules can become more complicated after a hospitalization, new diagnosis, or specialist visit. A current medication list shared with the family, prescribing clinician, pharmacy, and home care team can reduce confusion about what to take, when, and why.
CVS Pharmacy operates more than 9,000 locations nationwide and provides prescription services, immunizations, medication counseling, and refill support. As part of a coordinated plan, a Personal Health Care case manager may identify that missed doses are becoming a concern. At the same time, the family works with the pharmacy and prescribing provider to confirm the current regimen. Pharmacy support does not replace nursing care, but it can make a nursing or personal-care plan safer to follow.
Why It’s On The List
- Reliable prescription access supports recovery and chronic-condition management at home.
- Pharmacists can be a practical resource for routine medication questions and vaccination needs.
- It adds a medication-access layer without duplicating in-home nursing or personal care.
Philips Lifeline
Philips Lifeline represents the safety-technology portion of a complete plan. A medical alert device may help a person who lives alone, is at risk of falls, or spends time without a caregiver present. It can also provide reassurance to family members who cannot be in the home around the clock.
Before choosing an alert system, ask about cellular coverage at the home, fall-detection options, battery requirements, monitoring fees, emergency-response procedures, and caregiver notifications. A device is an added safety layer, not a substitute for skilled nursing, personal care, or emergency medical services.
Why It’s On The List
- It can extend safety support between scheduled caregiver visits.
- It may offer a faster way to request help when a person cannot reach a phone.
- It supports aging in place when paired with realistic supervision and emergency plans.
Independence Blue Cross
Independence Blue Cross can help families understand the financial and administrative side of a care plan. Before scheduling ongoing services, ask the member services team whether the individual’s plan covers home health, therapy, durable medical equipment, prescriptions, or private duty care. Families should also confirm in-network requirements, referrals, prior authorization, copayments, and documentation rules.
Coverage is not the same as care coordination. Personal Health Care can assess clinical and daily-living needs, while an insurer can explain the member’s benefit rules. For Medicare beneficiaries, home health coverage requirements explain that covered services generally require part-time or intermittent skilled care, homebound status, an order from a qualifying provider, and a Medicare-certified home health agency.
Why It’s On The List
- Early benefits verification can prevent avoidable delays or unexpected costs.
- It helps families distinguish covered skilled home health services from services that may require another payer or private payment.
- Insurance guidance supports, rather than replaces, clinical assessment and ongoing care management.
Building A Complete Home Care Plan
Start with a professional in-home assessment, then list the client’s medical, personal, nutritional, emotional, medication, and safety needs. Confirm payment options before services begin, choose one family contact to coordinate communication, and revisit the plan after a hospitalization, a fall, a medication change, or a decline in daily functioning. For Philadelphia families, Personal Health Care can anchor that network with personalized in-home support while PCA, CVS Health, Philips Lifeline, and Independence Blue Cross address the connected needs that help make care at home more sustainable.
-
 NEWS1 year ago
Historical Churches in Manila
-
 TOPIC3 months ago
Unveiling AvTub: Your Ultimate Guide to the Best AV Content
-
 TOPIC1 year ago
Symbols of Hope: The 15th Belenismo sa Tarlac
-
 TOPIC1 year ago
RIZAL at 160: a Filipino Feat in Britain
-
 TOPIC1 year ago
Simbang Gabi and Kakanin
-
 TOPIC2 months ago
Understanding Fascisterne: Origins and Ideological Roots
-
 TOPIC1 year ago
“The Journey Beyond Fashion” – Ditta Sandico
-
 NEWS4 months ago
What Caused Delta Flight DL275 to Diverted LAX? A Detailed Breakdown